
The content on this page has been converted from PDF to HTML format using an artificial intelligence (AI) tool as part of our ongoing efforts to improve accessibility and usability of our publications. Note:
- No human verification has been conducted of the converted content.
- While we strive for accuracy errors or omissions may exist.
- This content is provided for informational purposes only and should not be relied upon as a definitive or authoritative source.
- For the official and verified version of the publication, refer to the original PDF document.
If you identify any inaccuracies or have concerns about the content, please contact us at [email protected].
AS TM1 Accumulation Rates – Technical Analysis as at 30 September 2026
The FRC does not accept any liability to any party for any loss, damage or costs howsoever arising, whether directly or indirectly, whether in contract, tort or otherwise from any action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from any omission from it.
The Financial Reporting Council Limited 2026
The Financial Reporting Council Limited is a company limited by guarantee.
Registered in England number 2486368. Registered Office:
13th Floor, 1 Harbour Exchange Square, London E14 9GE
1. Executive Summary
1.1The Financial Reporting Council ('FRC') published AS TM1 v5.2 in February 2026 and it has been effective since 6 April 2026. The FRC carries out annual reviews to ensure the accumulation rate assumptions and volatility group boundaries remain appropriate.
1.2Following last year's review of market conditions as at 30 September 2025, the FRC made no changes to the actuarial assumptions in AS TM1 but published AS TM1 v5.2 (effective from 6 April 2026) containing only minor wording amendments relating to fund volatility calculation dates to clarify the FRC's policy intention.
1.3This paper sets out our review of the accumulation rate and volatility assumption based on data up to 30 September 2026.
Volatility group boundaries
1.4Our technical analysis based on data up to 30 September 2026 shows relatively little change in overall market volatility since 30 September 2025, the date on which the previous review was based.
Accumulation rates
1.5Our analysis of historical fund returns using data to 30 September 2026 does not show a significant increase in long-term historical returns compared to the previous analysis.
1.6The accumulation rates in AS TM1 v5.0 were set based on market conditions at 31 August 2021 and these rates were updated in v5.1 based on market conditions at 30 September 2023, noting in particular that there was evidence of a more sustained move to a higher interest rate environment.
1.7Following last year's annual review using market conditions at 30 September 2025, although there had been some further increase in interest rates, the FRC considered at that time that there was insufficient evidence of a sustained change in rates to support a further change to the accumulation rate assumptions.
1.8Since 30 September 2025 the increase in the real yields on long-dated gilts has been sustained (over 2%, compared to c-2.5% at 31 August 2021 and c1% at 30 September 2023, when the accumulation rates in AS TM1 were last amended). These yields could be considered an indicator of risk-free returns that can be achieved in excess of inflation and therefore a relevant benchmark for the FRC to consider when setting accumulation rates for lower risk asset types.
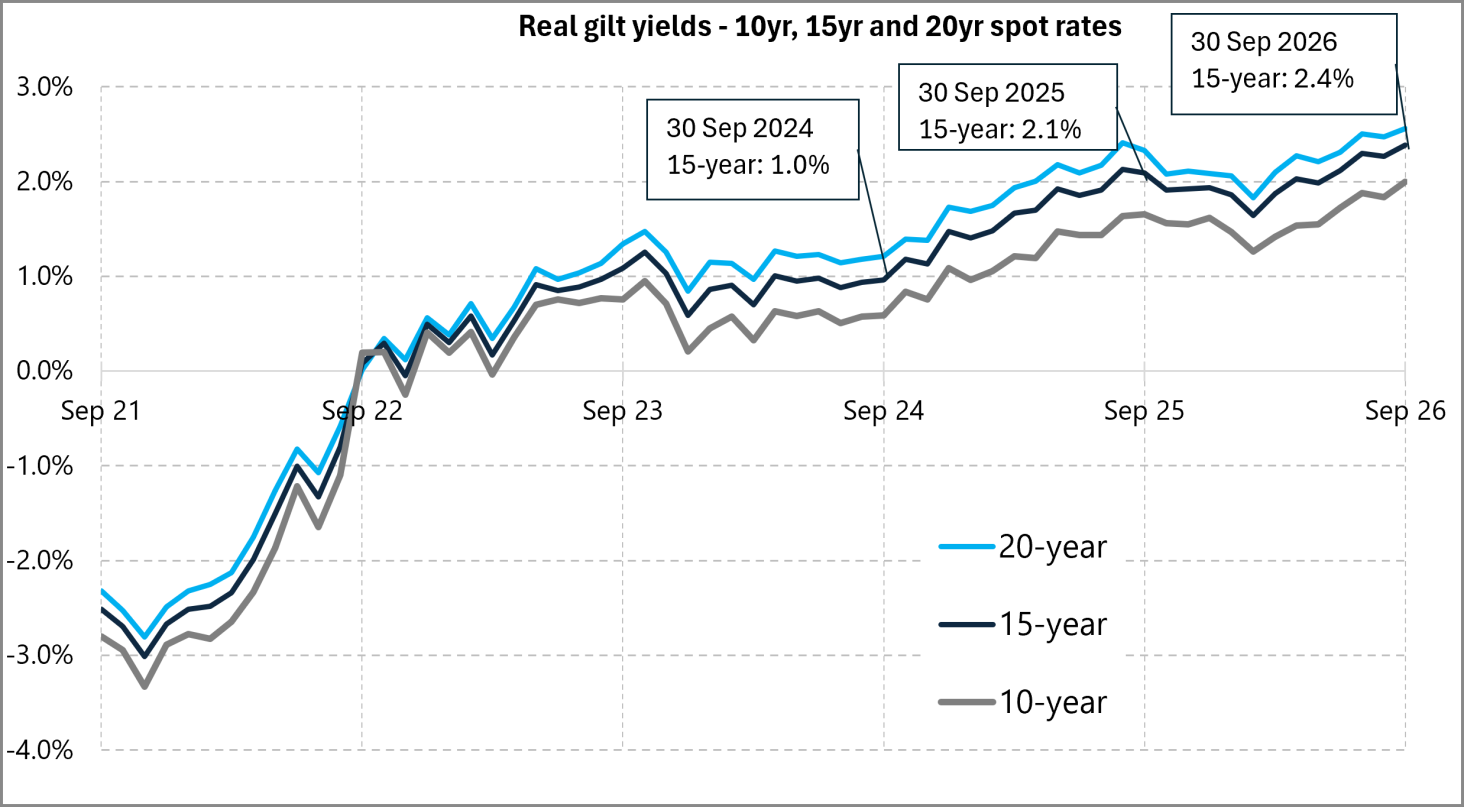
1.9The FRC now considers that in the environment of sustained long-dated real gilt yields of around 2% for the past year, the current accumulation rates for volatility groups 1 and 2 of 2% and 4%, i.e. real rates of -0.5% and 1.5%1, are no longer appropriate. This is particularly the case given volatility group 2 is expected to include some funds taking a certain level of risk, including corporate bond funds and some lower risk multi-asset funds. As a result, we consider it appropriate if the accumulation rate assumptions for volatility groups 1 and 2 were increased to 3% and 5% respectively, i.e. real rates of 0.5% and 2.5%. The real accumulation rate assumption of 0.5% for volatility group 1 would still be below the real gilt yield, to make some allowance for prudence in the assumption.
1.10Accumulation rate assumptions of 3% and 5% for volatility groups 1 and 2 respectively would also be more consistent with the assumptions for lower risk investments in third-party capital assumption pricing models, where these have been made available to us.
1.11We do not consider it appropriate to make a similar increase to the accumulation rates for volatility groups 3 and 4 at this time, as our technical analysis does not show a significant increase in the long-term returns observed on higher risk asset types which are expected to fall in these volatility groups. In addition, considering the views of external market commentators and third-party capital models where these are available to us, we believe a higher accumulation rate for these volatility groups might result in overly optimistic projections of some DC funds.
Overall
1.12The FRC considers there to be sufficient evidence to support a change in accumulation rate assumptions, given the sustained increase in real long-dated gilt yields since assumptions were last updated. The table below summarises the accumulation rate assumptions as set out in paragraphs C.2.4 and C.2.11 in AS TM1 v5.2 and the proposed changes as set out in the exposure draft of AS TM1 v5.3.
| Group | Volatility | Accumulation rate assumptions in AS TM1 v5.2 | Proposed accumulation rates assumptions in v5.3 | Implied real return in v5.3 vs. AS TM1 inflation assumption (2.5%) |
|---|---|---|---|---|
| 1 | 0% - 5% | 2% | 3% | 0.5% |
| 2 | 5% - 10% | 4% | 5% | 2.5% |
| 3 | 10% - 15% | 6% | 6% | 3.5% |
| 4 | Above 15% | 7% | 7% | 4.5% |
2. Context and scope
2.1Actuarial Standard Technical Memorandum 1: Statutory Money Purchase Illustrations (AS TM1) specifies the assumptions and methods to be used for the calculation of statutory illustrations of money purchase pensions (also known as defined contribution (DC) pensions) for annual Statutory Money Purchase Illustration (SMPI) statements, and Estimated Retirement Income (ERI) illustrated on pensions dashboards.
2.2The FRC reviews AS TM1 regularly and in the feedback statement for AS TM1 v5.0, we stated that we intend to review the boundaries between volatility groups, and the accumulation rate assumptions to be used for each volatility group, annually.
2.3This technical paper provides details of the analysis of data up to 30 September 2026 supporting our proposal (as set out in the consultation paper produced at the same time) to make no change to the volatility group boundaries, and to revise the accumulation rates.
2.4This paper should be read in conjunction with previous technical analyses on AS TM1 published by the FRC, in particular the technical paper issued in October 2022 which supported the development of AS TM1 v5.0 and considered data up to 31 August 2021.
2.5This paper covers:
- Data used within our updated analysis up to 30 September 2026
- Our analysis of the volatility group boundaries and
- Our analysis of the accumulation rates by volatility groups.
3. Data used
3.1The primary data set used in the analysis was obtained from Morningstar Direct. The data were checked, cleaned, and reconciled against the September 2025 data set. The data included 1,042 time series of monthly returns for UK wholesale pooled pension funds covering the period from 1 January 1985 to 30 September 2026. We conducted further checks and excluded some of the data from our analysis. For example:
- Some time series had missing returns for some months. For funds that remain extant, we understand that this results from the fund manager not reporting the fund's return in that month. The return reported in the following month does not include the return for the missing month. Therefore, any calculation of a volatility or a return which included a month with missing data was treated as null and excluded from the analysis. Funds with missing data were still included, but only for periods for which they had enough valid data to calculate the volatilities and returns required for the analysis.
- There were some funds which reported 0% returns in a given month. This differs from missing returns in that it indicates that a return of 0% was actually reported. We understand in some cases these could be genuine 0% returns, whereas in others these were a result of reporting stale prices. Within our analysis for any individual time series, we excluded periods where more than 5% of returns were reported as zero. For money market funds, we extend this to allow up to 25% of reported returns being zero, as genuine zero returns were expected to be more common for these funds.
- There were a small number of funds that included one or more monthly returns that are significant outliers compared to the returns for all similar funds for those months. These funds have been included in the analysis but with those particular monthly returns amended to 0%.
3.2The analysis described in this paper (as well as our previous technical papers) was based on UK wholesale pooled pension funds, which we consider adequately covers the types of funds typically used by UK money purchase pension schemes. We note, however, that fund size information was in places incomplete or may be an old figure. In addition, this may be the total size of a fund, where only a proportion of the investment in the fund is from UK money purchase pension schemes. Where fund size was not available, we have assumed the average value across those funds where it was available.
3.3We are aware that there may be some survivorship bias in the returns data as some poorer performing funds may have been merged into better performing funds. We consider the adjustment made for prudence in the accumulation rates is sufficient to allow for this.
4. Volatility boundaries
Purpose
4.1The purpose of this analysis was to test whether the existing set of volatility groups remains appropriate. As set out in section 5.1 of the Technical Analysis published in October 2022 we aim to establish a set of volatility groups which meet the following principles:
- Funds in the same group should be sufficiently homogenous that it is reasonable to project them with the same accumulation rate
- Funds in different groups should generally be discernibly heterogeneous such that it is reasonable to project them with different accumulation rates
- The group ranges should strike a balance between being sufficiently broad that funds will change between them infrequently, but retain a reasonably small step change in accumulation rate assumption between different groups
- The groups should be appropriate under the prevailing market conditions at the point at which providers are required to calculate their 5-year volatilities
- We should avoid spurious accuracy in drawing the boundaries between groups.
4.2We have also considered the extent to which funds would move between volatility groups under the current boundaries and if boundaries were to be changed.
Change in volatilities
4.3In previous analyses, we sub-divided the data into broad asset groupings (on an approximate basis from fund names and various classifications in the Morningstar data) and considered the historical rolling volatility of each asset grouping, to determine whether there is a clear separation in the volatilities between broad asset groupings.
4.4The analysis has been updated to include data up to 30 September 2026 and the graph overleaf shows the 5-year median volatility from 1990 to 30 September 2026 (the dashed lines are at 30 September, the effective date of our previous annual reviews):
Median rolling 5-year volatility by Fund type
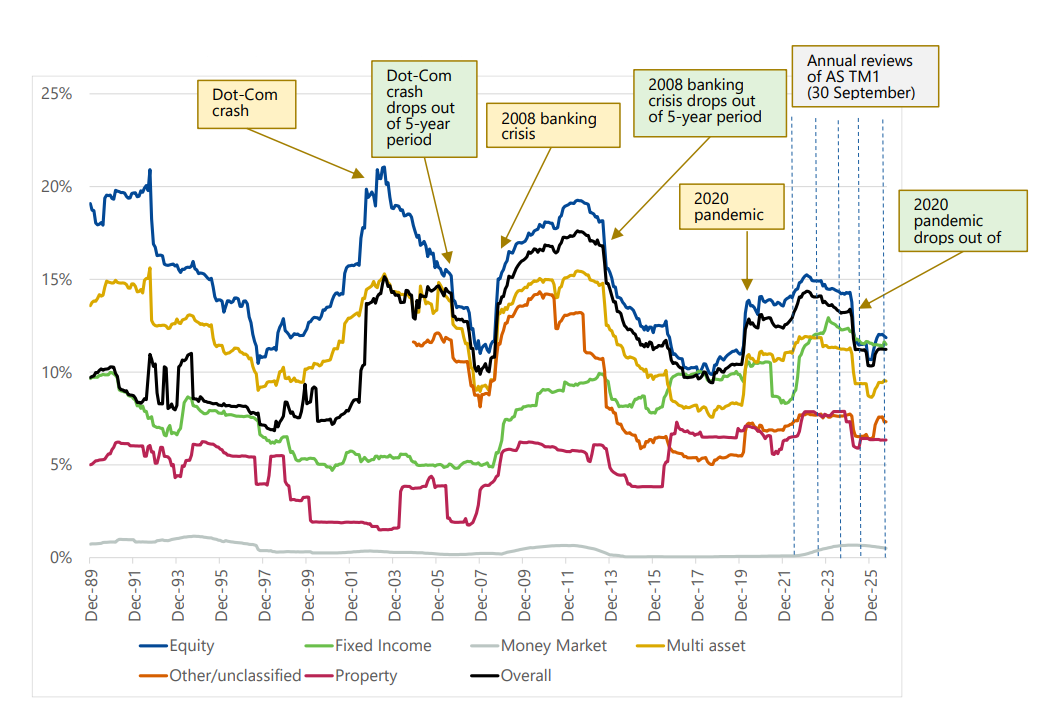
4.5From time to time, significant market events cause a step change in 5-year volatilities seen across the market. The FRC's intention is to recalibrate the volatility groups if the boundaries are no longer appropriate. We observed a fall in 5-year volatility as the impact of the 2020 pandemic fell out of the 5-year period at the time of the September 2025 review. This was considered relatively small in the context of the past 30 years and so no updates were made to the volatility group boundaries at that time.
4.6To show recent movements in volatilities more clearly, the following graph zooms in on the period since 30 September 2021:
Median rolling 5-year volatility by Fund type since September 2021
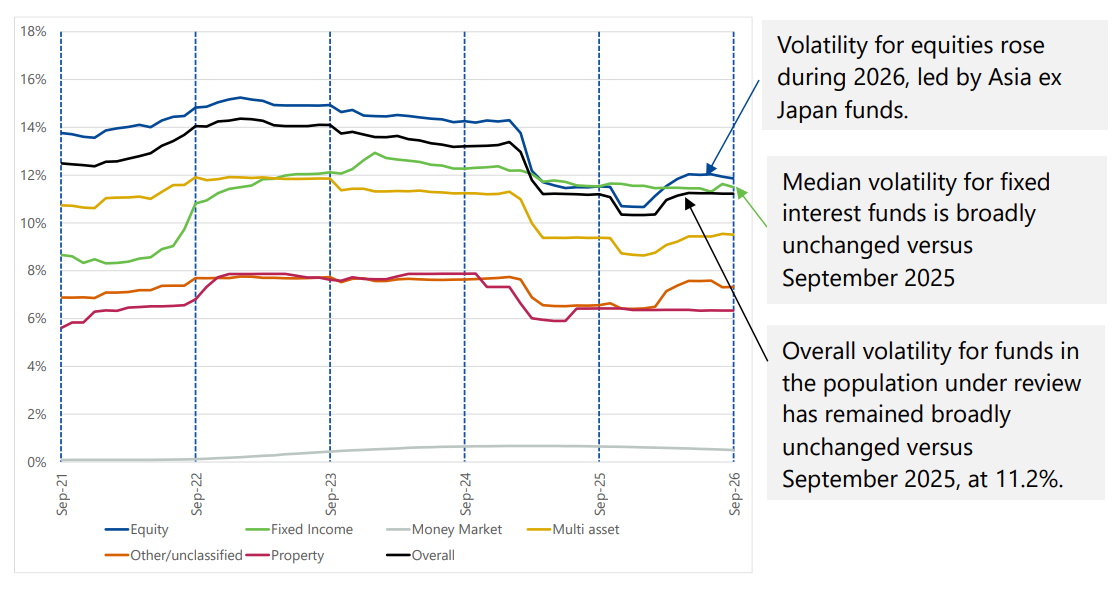
4.7Since the previous annual review at 30 September 2025, there has been relatively little change in overall fund volatility (the black line) although there have been small increases in equity volatility, offset by slight falls in fixed income volatility.
4.8Mean changes in fund volatilities by fund types are broadly in line with the change in the volatility of relevant indices:
| Fund type | Mean change in volatility of funds in data | Index | Change in volatility of the index |
|---|---|---|---|
| Equity | +0.4% | FTSE All World | +0.1% |
| Corporate bonds | -0.1% | iBoxx £ Corporate bond index2 | -0.1% |
| Fixed interest gilts | -0.3% | FTSE Actuaries UK Conventional Gilts All Stock | -0.2% |
| Index linked gilts | -0.4% | FTSE Actuaries Govt Securities UK Linked Market Value All Stocks | -0.5% |
4.9The chart below sets out the 5-year volatilities of the main fund types as at 30 September 2026.
Volatility groups – main fund types by value 30 September 2026
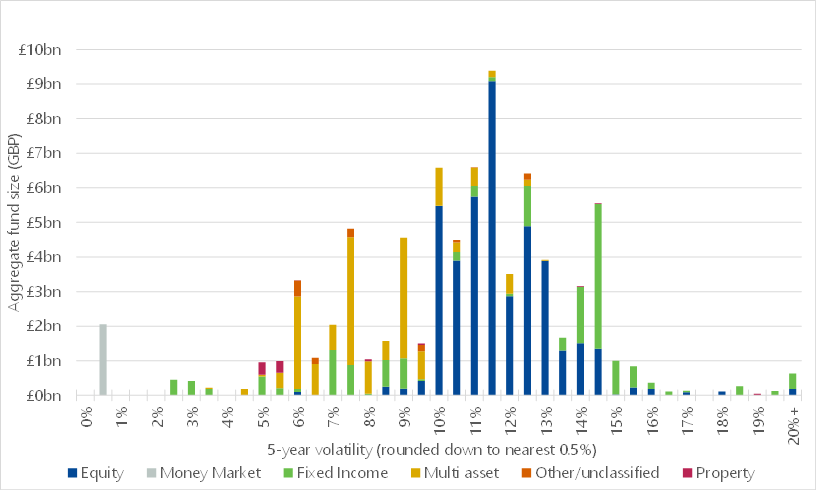
We observe:
- Equity funds volatility is generally in the range 10%-15% and maintaining a boundary of around 15% would place most equity funds in Group 3. Given the small increase in equity volatility, a small number of funds would move up to group 4 compared to 30 September 2025.
- Fixed income funds still span a range of volatilities, and a significant proportion of fixed income funds still have a volatility of 12% or more placing them in Group 3 or 4.
- The majority of multi-asset funds still lie in the range of 5%-10% placing them in Group 2.
- Money market funds consistently sit at a very low volatility (0 to 1%).
4.10For comparison, the next chart shows the equivalent position at the time of the 30 September 2025 annual review. Further comparison of the distribution of each of the broad fund types across the four volatility groups is provided in the Appendix.
Volatility groups – main fund types by value 30 September 2025
4.11The broad grouping of fixed income funds consists of funds which are invested in conventional gilts (fixed), index-linked gilts, corporate bonds, and other types of bonds. These are distributed as follows:
Volatility breakdown by fund type for Fixed Income only – 30 September 2026
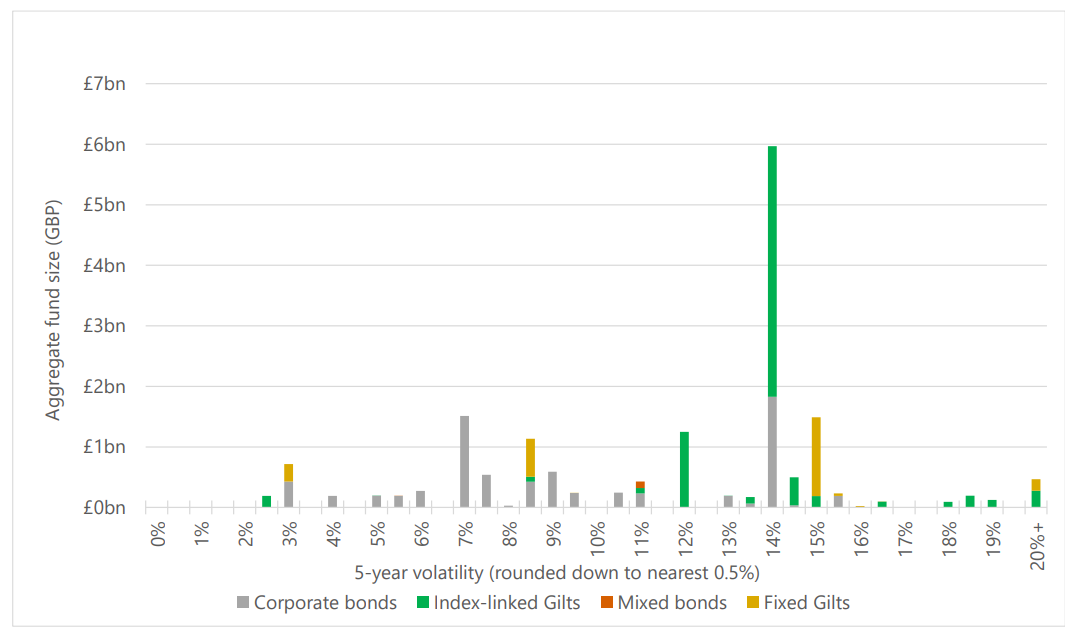
4.12The majority of the fixed income funds with a 5-year volatility above 10% are index-linked gilts (ILGs) (although we also observe a number of corporate bond funds in this group – see paragraph 4.14 below). We expect ILGs in general to have higher volatilities relative to their expected return than other funds. This results from long-dated ILGs potentially having a volatile market price (as their long duration makes them sensitive to long term real interest rate movements) but, as for conventional gilts, not being expected to earn a significant risk premium. This disconnection between volatility and expected returns for ILGs has arguably increased due to market movements since September 2022, with some ILG and fixed gilt funds still having a volatility above 15% placing them in volatility group 4 (under the existing volatility group boundaries).
4.13The higher volatility of ILGs was considered and commented on in the consultation on AS TM1 published February 2022, and we considered it was acceptable due to the relatively low prevalence of ILG investment in money purchase funds, particularly for savers further from retirement where the accumulation rate has the most significant impact on the pension illustrations. Engagement with industry representatives has confirmed that there is typically a low prevalence of ILGs invested for savers further from retirement age, and this is supported by independent research carried out for the FRC. The 5-year historical volatility of ILGs is expected to fall when the 2022 volatility spike moves out of the 5-year window in 2027.
4.14Corporate bond funds span a wide range of volatilities. This is to be expected as this is a relatively broad asset class and could include a range of types of corporate bonds, including different levels of maturities. Corporate bond funds can differ significantly in both volatility and expected returns and therefore can reasonably be expected to span multiple volatility groups.
Movement of funds between groups
4.15Given the small movements in market volatility for some asset types described in paragraph 4.7 above, maintaining the existing rates would result in some funds moving to a different volatility group. We therefore conducted further analysis to understand these movements and how this may differ under alternative volatility group boundaries.
4.16We considered the proportion of funds (weighted by fund value) within our data set that would be categorised into a different volatility group if we maintained the current boundaries between volatility groups, without applying the 0.5% corridor as specified in C.2.12 of AS TM1. The table below shows the categorisation of funds given current boundaries based on volatilities at 30 September 2025 and 30 September 2026, and shows few funds changing group over the period.
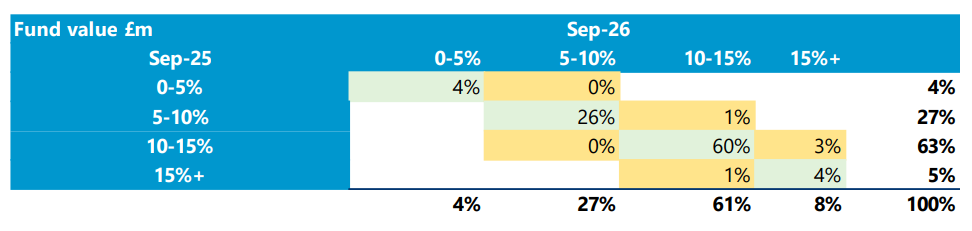
4.17Our analysis showed that any change to the volatility group boundaries would result in a greater number of funds moving between volatility groups than as set out above.
Conclusion
4.18Given the relatively minor small changes in volatility to 30 September 2026, we consider the volatility group boundaries remain appropriate.
4.19It is useful to bear in mind that although the data set (which is based on UK wholesale pooled pension funds) adequately covers the types of funds typically used by UK money purchase pension schemes, the data set is not expected to capture all money purchase investments in the UK. Therefore, the analysis can only be an illustration informing us of the likely impact on the movement of actual funds held, rather than a comprehensive investigation of the distribution of actual funds.
5. Accumulation rates
5.1The determination of the appropriate accumulation rate assumption for each volatility group is a subjective process and requires an element of judgement to be applied to the results of any statistical analysis. We have based our updated analysis on the approach in the technical paper published in October 2022, which sets out how we used a combination of backward-looking data-driven analysis and judgement-based forward-looking analysis.
5.2AS TM1's methods and assumptions are used for the purpose of general pension illustration, rather than an accurate individualised pension projection. The FRC considers it important that the resulting accumulation rate assumptions can be determined consistently for different funds, and the resulting statutory illustration should be easy to describe to savers and to be understood by them. Our intention continues to be to avoid significant changes in accumulation rate assumptions from one period to the next, to the extent that the accumulation rates remain appropriate.
Analysis of past experience
5.3This analysis is based on considering past returns but with specific adjustments made e.g. where our view was that past returns may not be repeated in the future. The derivation is set out in more detail within the October 2022 technical paper. The results of the September 2025 analysis are reproduced below.
| Group | Latest data analysis at 30/09/2025 | Adjust for bond effect | Adjust for prudence | Implied rate (unrounded) | Implied rate (rounded) |
|---|---|---|---|---|---|
| 1 | 1.4% | -1.0% | 0.4% | 0% | |
| 2 | 5.0% | -1.0% | -1.5% | 2.5% | 3% |
| 3 | 7.1% | -0.25% | -1.5% | 5.4% | 5% |
| 4 | 8.8% | -1.5% | 7.3% | 7% |
5.4The analysis includes an adjustment for the 'bond effect', which intends to mitigate the excess returns seen for gilt funds in volatility groups 2 and 3 that resulted from the decline in long-dated bond yields over the period up to 2020. This was based on our view there was a natural floor to bond yields, and that therefore the past experience of significant reductions in long dated bond yields up to 2020 would not continue in future.
5.5The table below shows the updated analysis as at 30 September 2026.
| Group | Latest data analysis at 30/09/2026 | Adjust for bond effect | Adjust for prudence | Implied rate (unrounded) | Implied rate (rounded) |
|---|---|---|---|---|---|
| 1 | 1.4% | -1.0% | 0.4% | 0% | |
| 2 | 4.7% | -1.0% | -1.5% | 2.2% | 2% |
| 3 | 7.1% | -0.25% | -1.5% | 5.3% | 5% |
| 4 | 9.1% | -1.5% | 7.6% | 8% |
5.6We note that, first, the rate for groups 2 and 3 has fallen slightly owing to more recent falls in bond prices, and that, second, the rate for group 4 has increased slightly owing to positive returns in equity markets.
5.7As expected, there is limited change in the returns based on the historical data analysis. This results from the inherent smoothing in the chosen methodology. We consider a long-term expected return, which takes into account monthly returns over rolling 15-year periods from 1990 until 2026. This means in total there are 262 overlapping 15-year periods of returns considered (the first ending on 31 December 2004 and the last ending on 30 September 2026), of which only 12 are 'new' periods resulting in our updating analysis for the period from 30 September 2025 to 30 September 2026.
Analysis of long-dated interest rates
5.8As shown in the chart below, long dated real gilt yields (as an indicator of the risk-free returns that can be achieved in excess of inflation) have increased significantly since the initial technical analysis underlying AS TM1 v5.0 (which used data at 31 August 2021) with the 15-year real gilt yield rising from -2.7% to 2.4% at 30 September 2026.
5.9The increase in real gilt yields was considered in the rationale for increasing accumulation rate assumptions for funds in volatility groups 1, 2 and 3, when the FRC introduced AS TM1 v5.1 following the 30 September 2023 analysis. The 15-year real gilt yield was 1.1% at 30 September 2023.
5.10As noted in the technical analysis last year, although yields remained broadly stable over the year to September 2024, a further increase of c1%, occurred over the year to 30 September 2025. At the time, we considered that it was not clear whether this increase in real gilt yields will be sustained over time. From the chart above, we observe that the yields have remained at a similar level over the year to 30 September 2026. We consider there is now sufficient evidence that the rise in real long-dated gilt yields is sustained and the accumulation rate assumptions may no longer be appropriate in the higher long-term interest rate environment.
5.11We note that long-dated real gilt yields are sensitive to supply-demand by a concentrated number of market participants, i.e. pensions schemes and life insurers. It is therefore useful to also understand how long-dated real interest rate swap yields move over time. We note that long-dated swap yields have moved in a broadly similar way to gilt yields, which provides further evidence that the UK is in a higher long-term interest rate environment.
Analysis based on fund type
5.12We considered the accumulation rate assumptions that would be derived by incorporating a forward-looking view of the returns for each of the fund types sitting within each volatility group. This provides an additional perspective from which to consider potential future returns, compared to the output of the analysis described in paragraphs 5.3-5.6.
5.13For this analysis, the approach (as followed in last year's review) for considering the forward-looking return for each fund type is as follows:
- For money market and fixed income funds, the returns are based on the average of 15- and 20-year government bond yields.
- For corporate bond funds, the returns are based on the yield on the iBoxx Sterling Corporate Bond Index, with a broad adjustment for default risk (taken to be half of the spread between this corporate bond yield and the fixed interest government bond yield).
- For equity funds, given there is no specific indicator of future returns, the historical returns3 within our data set for that equity fund type (broken down by broad geographic regions) were used.
- The returns for property and unclassified funds were also based on the historical return as observed in the data.
- A 50/50 mix of corporate bonds and equities was assumed for multi-asset funds and the corresponding returns for each fund type as above were used. Although we have limited detail on the make-up of multi-asset funds in our dataset, we understand these funds to be predominantly a mixture of equities and bonds, and the historical returns on multi-asset funds in our dataset have been roughly halfway between the returns on corporate bond funds and the returns on equity funds.
5.14The resulting accumulation rate assumptions by volatility group are shown in the table below, alongside the figures from last year's review for comparison:
| Group | September 2025 Review Implied rate | September 2025 Review Implied rate (after rounding) | September 2026 Review Implied rate | September 2026 Review Implied rate (after rounding) |
|---|---|---|---|---|
| 1 | 4.8% | 5% | 4.9% | 5% |
| 2 | 6.5% | 6% | 6.9% | 7% |
| 3 | 7.7% | 8% | 8.1% | 8% |
| 4 | 6.0%4 | 6% | 7.8% | 8% |
5.15The increase in the rate for Group 4 arises because the proportion of Group 4 in equities has increased from 23% to 54% and some higher volatility equity funds have enjoyed a period of strong returns during 2026.
5.16There are limitations in using this analysis by fund type and so we do not consider it is appropriate to use these results alone in setting accumulation rates. This analysis can, however, alongside our analysis based on past returns, help inform an overall judgement of the appropriate accumulation rates to use. In particular, this analysis would potentially give accumulation rates that vary frequently, due to the sensitivity to changes in bond yields. There is also arguably an inconsistency in the approach which combines forward looking indicators for some fund types (e.g. gilts), and past returns for others (e.g. equities).
5.17This analysis also shows the same accumulation rate for group 4 as for group 3, despite it representing higher volatility investments. This results primarily from Group 4 continuing to hold a significant proportion (45%) of gilt funds (see paragraph 4.9) which have a lower assumed expected return (under this methodology) than the historical returns of the other funds in the group which are mainly equity funds. If we exclude fixed income funds from volatility group 4 in our analysis then the derived accumulation rate for group 4 would be 9.7%, higher than the rate derived for group 3. We note that gilt funds are a relatively small proportion of DC fund investments, particularly for savers further from retirement where the accumulation rate has the most significant impact on the pension illustrations. Therefore, we place limited weight on this result and have also considered what the value would be under this method if there were no bond funds in volatility group 4.
Benchmarking against third party assumptions
5.18We have considered the long-term return assumptions in a number of third-party capital asset pricing models ('CAPM's) made available to us and forecasts observed in the market which are publicly available across various asset classes. This analysis has considered models/forecasts used by 14 different organisations, including investment banks, investment advisors and investment management companies.
5.19For the organisations where we have seen updates to the model assumptions/forecasts since 30 September 2025, they show a mixture of updates, with some forecasting higher expected returns compared to last year and some forecasting lower expected returns compared to last year.
5.20For global equities the average long-term expected return is slightly lower than last year but still rounds to 7%, and with long-term expected returns ranging from around 4.5% to 8%, compared to last year's range of around 5% to 9.5%. A couple of the organisations who had assumptions towards the higher end the previous year have reduced their assumption for global equity returns by around 2%.
5.21For fixed income assets, we observe a small increase in the average long-term expected return. For gilts, long-term expected returns ranged from around 4.5% to 5.5% (compared to 4% to 5% last year) while for investment grade corporate bonds the long-term expected returns ranged from around 4%5 to 6% (the same as last year).
5.22For cash and money market assets, the average long-term expected return has fallen slightly to 3.3% (from 3.5% last year) with the range moving down to around 2.5% to 4% (compared to 3% to 4.5% last year).
5.23The assumptions observed for UK CPI inflation (where given) continue to fall within the range from around 2% to 2.5%, which is the same as the previous year.
5.24We review third party models/forecasts as a broad check against our analysis of accumulation rates but we note that we can place only limited reliance on this. The set of forecasts we have used is limited to those made available to us from some of the major industry sources. There are also known inconsistencies between projection methodologies which limits use of this analysis beyond a check for reasonableness. For example:
- some forecasts are provided in USD terms rather than GBP, meaning that part of the forecasts may be due to expected currency exchange movements (which we have not attempted to adjust for)
- different forecasts are updated at different points in the year, so the year-on-year changes may refer to different periods of time (at the time of our annual review, some forecasts are a year out of date); and
- most are 10-year forecasts but some are 7-year, 20-year, or an unspecified 'long' time horizon.
Conclusion
5.25Our analysis on data to 30 September 2026 again shows limited change based on our analysis of historical returns. Higher real long-dated gilt yields (compared to those at 31 August 2021 which informed AS TM1 v5.0) have continued. Since the accumulation rates were updated based on 30 September 2023 conditions, the additional c1% increase which occurred between 30 September 2024 and 30 September 2025 has been sustained over the year to 30 September 2026.
5.26These real long-dated gilt yields could be considered an indicator of risk-free returns that can be achieved in excess of inflation, and therefore a relevant benchmark for the FRC to consider when setting accumulation rates for lower risk asset types, although many commentators would expect a lower yield on money market funds to reflect their shorter-term nature.
5.27The FRC now considers that in an environment of sustained long-dated real gilt yields in excess of 1% (for the past 3 years) and currently around 2% for the past year, the current accumulation rates for volatility groups 1 and 2 of 2% and 4%, i.e. real rates of -0.5% and 1.5%6, are no longer appropriate. This is particularly the case given volatility group 2 is expected to include some funds taking a certain level of risk, including corporate bond funds and the majority of multi-asset funds. As a result, we consider it appropriate if the accumulation rates assumptions for volatility groups 1 and 2 were increased to 3% and 5% respectively, i.e. real rates of 0.5% and 2.5%. The real accumulation rate assumption of 0.5% for volatility group 1 would still be considerably below the real gilt yield, to make some allowance for prudence in the assumption.
5.28Accumulation rate assumptions of 3% and 5% for volatility groups 1 and 2 respectively would be more consistent with the assumptions for lower risk investments in third-party capital assumption pricing models (where these have been made available to us) where the long-term expected return for cash is around 3.3% on average and the long-term expected return for investment grade corporate bonds is around 5% on average. For multi-asset funds, most of which are currently expected to be in volatility group 2, we would expect the third-party assumptions to be higher still given that such funds typically include some exposure to asset classes such as equities.
5.29We consider it inappropriate to make a similar increase to the accumulation rates for volatility groups 3 and 4 at this time, as our technical analysis does not show a significant increase in the long-term returns observed on higher risk asset types which are expected to fall in these volatility groups. In addition, considering the views of external market commentators and third-party capital models where these are available to us we believe a higher accumulation rate for these volatility groups might result in overly optimistic projections of some DC funds.
6. Appendix
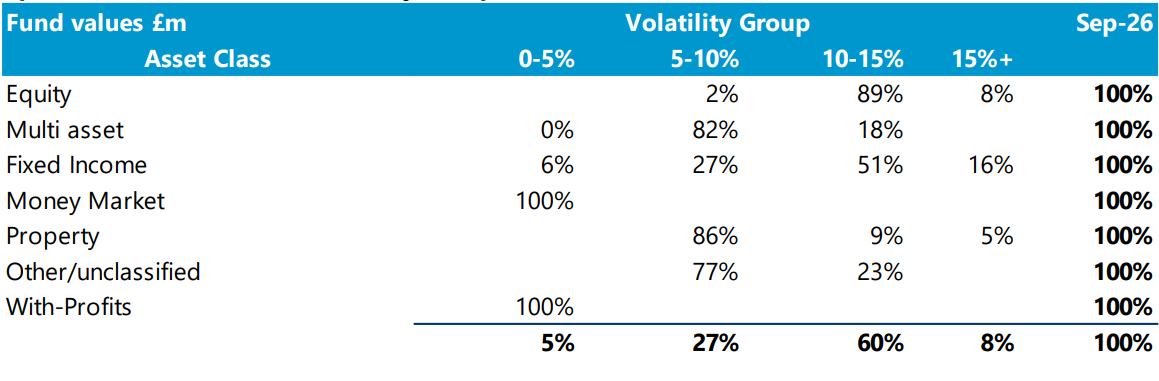
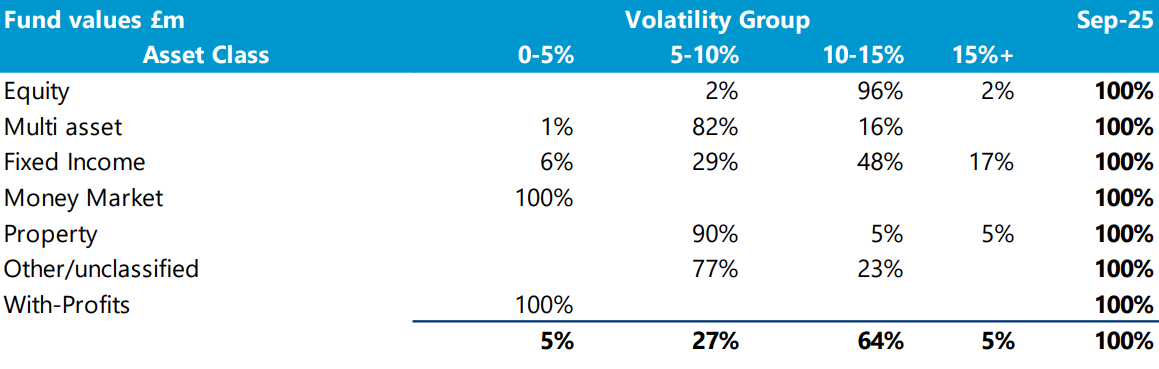
The tables below provide further information on the comparison of the distribution of each of the broad fund types across the four volatility groups as at 30 September 2026 and 30 September 2025 as seen in paragraphs 4.9 and 4.10.7
At 30 September 2026
Split of Asset Class across Volatility Groups
At 30 September 2025
Split of Asset Class across Volatility Groups
Financial Reporting Council
London office:
13th Floor, 1 Harbour
Exchange Square,
London, E14 9GE
Birmingham office:
5th Floor, 3 Arena
Central, Bridge Street,
Birmingham, B1 2AX
+44 (0)20 7492 2300
Follow us on LinkedIn
Footnotes
-
relative to the AS TM1 inflation assumption of 2.5% ↩
-
Uses returns from S&P U.K. Investment Grade Corporate Bond Index prior to August 2024. ↩
-
The returns used are the annualised geometric average return for the fund since 1 January 1985, or inception if later. As the number of funds in our data set increases over time, only a small proportion of returns cover the full period back to 1985. ↩
-
Increases to 9.7% when bonds are excluded from Group 4 (8.8% for Sep 2025). ↩
-
The lower end of the range for investment grade corporate bonds was lower than for gilts. This is because one third party model had an assumption of 4% for investment grade corporate bonds but no assumption provided for gilts. All the models that provided assumptions for both investment grade corporate bonds and gilts had a higher expected return for investment grade corporate bonds. ↩
-
relative to the AS TM1 inflation assumption of 2.5% ↩
-
These tables are based on all the funds with a 5-year volatility value at 30 September 2026 for current year table and all funds with a 5-year volatility value at 30 September 2025 for last year. These are not precisely comparable to the figures in paragraphs 4.15-4.16 which only consider funds that had 5-year volatility values both at 30 September 2025 and at 30 September 2026. ↩