
The content on this page has been converted from PDF to HTML format using an artificial intelligence (AI) tool as part of our ongoing efforts to improve accessibility and usability of our publications. Note:
- No human verification has been conducted of the converted content.
- While we strive for accuracy errors or omissions may exist.
- This content is provided for informational purposes only and should not be relied upon as a definitive or authoritative source.
- For the official and verified version of the publication, refer to the original PDF document.
If you identify any inaccuracies or have concerns about the content, please contact us at [email protected].
The UK and Irish Digital Reporting Taxonomies Guide 2027
The FRC does not accept any liability to any party for any loss, damage or costs howsoever arising, whether directly or indirectly, whether in contract, tort or otherwise from any action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from any omission from it.
The Financial Reporting Council Limited 2026
The Financial Reporting Council Limited is a company limited by guarantee. Registered in England number
- Registered Office: 13th Floor, 1 Harbour Exchange Square, London E14 9GE
- 1. Introduction
- 2. UK and Irish Digital Reporting Taxonomies
- 3. Taxonomy Design features
- 3.2. Dimensions
- 3.4 Label Linkbase
- 3.5 Presentation Linkbase
- 3.6 Definition Linkbase
- 3.7 Reference Linkbase
- 3.8 Other technical information
- 4. Implementation Guidance for Preparers and Software Developers
- 4.5 No tag available
- 4.6 Alternative tags
- 4.7 Unique application of tags
- 4.8 Tagging of multiple occurrences of data items
- 4.9 Fixed value tags
- 4.10 Boolean tags
- 4.11 Tagging of numeric data
- 4.12 Tagging of text
- 4.13 Tagging of numeric data presented within text
- 4.14 Explicit dimension default members
- 4.15 Use of generic dimension domain members
- 4.16 Use of ‘non-standard' and 'further item' dimension domain members
- 4.17 Use of further item concepts and analysis typed dimension
- 4.18 Use of grouping tags
- 4.19 Entity information
- 4.20 Period information
- 4.21 Unit information
- 4.22 Currencies
- 4.22.1 RULE
- 4.23 Scale and Accuracy of values
- 4.23.1 RULE
- 4.23.2 RULE
- 4.24 Positive and negative values
- 4.24.1 RULE
- 4.24.2 RULE
- 4.24.3 RULE
- 4.25 Use of 'free-text comment' tags
- 4.25.1 RULE
- 4.26 Nesting of Tags
- 4.26.1 RULE
- 4.27 Tagging of footnotes
- 4.28 Dates
- 4.28.1 RULE
- 4.29 Percentages
- 4.29.1 RULE
- 4.30 Unreported data
- 4.30.1 RULE
- 4.31 Use of XBRL nil values
- 4.32 Tagging of comparative data
- 4.32.1 RULE
- 4.33 Compulsory tags
- 4.34 Distinction of company and group data
- 4.34.1 RULE
- 4.35 Revised data
- 4.36 Completeness, accuracy and summation
- 4.36.1 RULE
- 4.37 Summation and checking of tagging
- 4.38 Taxonomy Extensions
- 4.38.1 RULE
- Appendices
- B: Data types
- C: Fixed value tags
- D: Generic dimensions
- E: Arcs and arcroles
- F: Roles
- G: References
- H: Taxonomy file structure
1. Introduction
1.1. Context
Digital reporting has evolved from manual, paper-based processes and unstructured formats like PDFs to structured, machine-readable formats such as extensible Business Reporting Language (XBRL). XBRL is the global standard for digital reporting, providing a framework in which financial, narrative, and other disclosures can be tagged to produce structured, machine-readable report. An XBRL report (technically termed an “instance document") is a digital report where information is structured according to the XBRL standard, enabling it to be automatically identified, extracted, and analysed by software. The XBRL standard defines a number of different formats for XBRL reports, including Inline XBRL (iXBRL), xBRL-XML, xBRL-CSV and xBRL-JSON.
Every XBRL report refers to a specific taxonomy entry point, and it is the combination of the report and the taxonomy that enables the contents to be fully understood. For instance, a UK entity filing its annual report would reference a specific entry point within the FRC taxonomy suite, such as the FRS 102 entry point. The entry point provides access to the underlying elements, identifying a specific subset of the taxonomy that has been tailored for a particular reporting purpose.
A taxonomy digitises disclosure requirements into a structured digital format, enabling entities to submit their regulatory filings as an XBRL report. A taxonomy package consists of multiple schema (.xsd) and linkbase (.xml) files. The schema files define the elements and their attributes. The most critical elements are concepts, dimensions, and hypercubes. A concept (often referred to as a "line item tag") defines the nature of the information being reported, such as "Turnover". Dimensions and associated domain members (often referred to as "dimension tags") act as qualifying characteristics. Hypercubes organise concepts and dimensions into multi-dimensional structures, defining the allowable reporting combinations.
The taxonomy linkbases establish relationships between elements, using specific arcroles to define the nature of these connections, to organise them into hierarchies and logical structures, while also mapping those elements to human-readable labels and the relevant reporting standards or legislation.
The individual piece of machine-readable data within an XBRL report is known as a fact. A fact comprises a reported value (a numerical or narrative disclosure) tagged with specific contextual metadata. This contextual metadata comprises different aspects; specific examples include the concept (business meaning), the period (timeframe), the entity's identity, and any dimensions required to further qualify the data. Together, these aspects ensure that every fact is uniquely identified.
To serve both human reviewers and automated processing, iXBRL reports are widely used across multiple jurisdictions. An iXBRL report combines a human-readable presentation with structured, machine-readable data in a single document. By embedding XBRL data into an HTML file, iXBRL allows preparers to retain full control over the visual layout of their reports while ensuring the data can be automatically processed by collectors and consumers.
1.2. Scope
The Financial Reporting Council (FRC) develop and maintain the UK and Irish digital reporting taxonomies on behalf of a cross-government group of departments and regulators. These taxonomies digitise reporting standards and regulations, enabling entities to submit regulatory filings in a machine-readable, structured format. This is aimed at fostering a technologically advanced ecosystem for exchanging financial, sustainability, and other data among preparers, data collectors, and data consumers. Taxonomy development is overseen by longstanding, multi-stakeholder governance bodies: the XBRL UK Technical Task Force, the XBRL UK Governance Committee, and the FRC Executive Committee.
The UK and Irish digital reporting taxonomies include:
- The FRC Taxonomy Suite
- The Irish Revenue Taxonomy
- The Charities Taxonomy
The taxonomies define elements for UK-adopted IFRS Accounting Standards endorsed by the UK Endorsement Board, EU-adopted IFRS Accounting Standards, UK and Ireland accounting standards issued by the FRC, such as FRS 101 Reduced Disclosure Framework, FRS 102 The Financial Reporting Standard applicable in the UK and Republic of Ireland, FRS 103 Insurance Contracts and FRS 105 The Financial Reporting Standard applicable to the Micro-entities Regime. The taxonomies also incorporate International Standards on Auditing (UK) (ISAs (UK)) issued by the FRC and International Standards on Auditing (Ireland) (ISAs (Ireland)) issued by IAASA, and legislative requirements, such as the Companies Act, the Charities Act, TCFD and SECR regulation.
The FRC Taxonomy Suite also accommodates entry points for Community Interest Company Report (CIC 34) and Dormant Subsidiary Exempt Package (DSEP) accounts.
The Charities taxonomy digitises disclosure requirements for the Charities Statement of Recommended Practice (SORP) issued by the Charities SORP-making body.
Current and historical versions of the taxonomy packages (ZIP files) are available on the FRC website, and are accompanied by versioning reports detailing changes made.
Taxonomies are intended to be viewed and used in appropriate XBRL software. Spreadsheet or similar text files are useful to look at the changes but are not recommended for general use, as they are not able to represent taxonomy content and features clearly and effectively. The taxonomies are also available for viewing and exploration via the online Taxonomy Viewer tool.
Annual update
The taxonomies are updated annually to reflect amendments in the standards and practical usage feedback. This regular annual update cycle ensures that the taxonomies remain fully aligned with all subsequent amendments to the underlying accounting, auditing, and other standards.
1.3. Target Audience
Before a taxonomy is finalised and issued, a draft version is published for public consultation. Once ready, the taxonomy packages are published on the FRC website at URLs that match the locations declared within the files themselves. Software developers may use these official packages as authoritative references for taxonomy content.
This guide consolidates the Accounts Taxonomies Design guide, Tagging Guide, Developer Guide into a single, comprehensive resource to streamline the implementation process for all stakeholders.
This guide provides a technical overview of the architectural design, applying to all three taxonomies unless otherwise stated. It assumes that readers are familiar with the XBRL standard, and it is intended to assist four primary user groups:
- Preparers: Professionals responsible for the digital tagging of reports and accounts using taxonomies, ensuring compliance with regulatory requirements.
- Data Collectors: These are the regulatory bodies responsible for receiving the iXBRL reports for official purposes (e.g. Companies House, His Majesty's Revenue and Customs (HMRC), the Financial Conduct Authority (FCA), the Charity Commission for England and Wales (CCEW), and the Office of the Revenue Commissioners of Ireland (Irish Revenue)).
- Data Consumers: Users who consume the facts from the iXBRL reports to make informed decisions, such as analysts, investors, and academics.
- Software Developers: Users who build and maintain the software necessary for the tagging, validation, and consumption of iXBRL reports.
For additional information and supporting documentation from data collectors, please refer to the References appendix.
1.4. Comments and questions
Please direct comments and questions on this guide to [email protected].
2. UK and Irish Digital Reporting Taxonomies
2.1. Taxonomy entry points
A taxonomy entry point serves as the logical starting point for both preparing and consuming an iXBRL report. This section lists the available entry points in the taxonomies.
2.1.1. FRC Taxonomy Suite
The FRC Taxonomy Suite provides the following entry points for preparing a report:
FRS-102
This entry point is useful for entities filing their financial statements prepared in accordance with FRS 102 The Financial Reporting Standard applicable in the UK and Republic of Ireland, FRS 103 Insurance Contracts or FRS 105 The Financial Reporting Standard applicable to the Micro-entities Regime.
IFRS
This entry point is useful for entities filing their financial statements prepared in accordance with UK-adopted IFRS Accounting Standards.
FRS-101
This entry point is useful for entities filing their financial statements prepared in accordance with FRS 101 Reduced Disclosure Framework. It enables qualifying subsidiaries and ultimate parent companies to take advantage of disclosure exemptions in comparison to the requirements in IFRS Accounting Standards.
DPL
This entry point defines elements for Detailed Profit & Loss statements. All elements available within this entry point are also available via other applicable entry points.
CIC-34
This entry point is useful for community interest companies (CICs) filing their CIC-34 company report prepared in accordance with requirements stipulated in section 34 of the Companies (Audit, Investigations and Community Enterprise) Act 2004 and Part 7 of the Community Interest Company Regulations 2005 (SI 2005/1788).
DSEP-AA06
This entry point is useful for entities filing the statement of guarantee from the parent company (form AA06) as part of the Dormant Subsidiary Exempt Package, applicable to both filing-exempt and audit-exempt subsidiaries.
DSEP-Agreement
This entry point is useful for entities filing the written notice of agreement by the subsidiary's members under the Dormant Subsidiary Exempt Package, applicable to both filing-exempt and audit-exempt subsidiaries.
IFRS-UKSEF
This entry point is useful for entities filing their annual consolidated report using the multiple target documents approach (UKSEF approach). It enables preparers to utilise elements from the FRC Taxonomy Suite for the “UKFRS” target document, allowing them to submit parent company data in digital format to Companies House. This entry point is equivalent to the corresponding IFRS entry point, but preparers are required to use the UKSEF variants to ensure that any future UKSEF-specific variations or additions to the FRC Taxonomy Suite are in scope of the report.
FRS-102-UKSEF
This entry point is useful for entities filing their annual consolidated report using the multiple target documents approach (UKSEF approach). It enables preparers to utilise elements from the FRC Taxonomy Suite for the “UKFRS” target document, allowing them to submit parent company data in digital format to Companies House. This entry point is equivalent to the corresponding FRS-102 entry point, but preparers are required to use the UKSEF variants to ensure that any future UKSEF-specific variations or additions to the FRC Taxonomy Suite are in scope of the report.
2.1.2. Charities Taxonomy
The Charities Taxonomy provides one entry point for preparing a report:
Charities
This entry point extends FRS-102 from the FRC Taxonomy Suite and defines additional elements for the Statement of Recommended Practice (SORP) applicable to charities preparing their accounts in accordance with FRS 102 The Financial Reporting Standard applicable in the UK and Republic of Ireland.
2.1.3. Irish Revenue Taxonomy
The Irish Revenue Taxonomy provides the following entry points for preparing a report:
FRS-102
This entry point extends FRS-102 from the FRC Taxonomy Suite and is useful for entities filing their financial statements prepared in accordance with FRS 102 The Financial Reporting Standard applicable in the UK and Republic of Ireland, FRS 103 Insurance Contracts or FRS 105 The Financial Reporting Standard applicable to the Micro-entities Regime to the Revenue Commissioners of Ireland.
EU IFRS
This entry point extends IFRS from the FRC Taxonomy Suite and is useful for entities filing their financial statements prepared in accordance with EU-adopted IFRS Accounting Standards to the Revenue Commissioners of Ireland.
FRS-101
This entry point extends FRS-101 from the FRC Taxonomy Suite and is useful for entities filing their financial statements prepared in accordance with FRS 101 Reduced Disclosure Framework to the Revenue Commissioners of Ireland. It enables subsidiaries and ultimate parent companies to take advantage of disclosure exemptions in comparison to the requirements in IFRS Accounting Standards.
2.2. UKSEF approach
UKSEF enables filing to the FCA (for certain listed companies DTR 4.1 disclosures) and Companies House (UK company law disclosures) using one tagged iXBRL report. The UKSEF approach uses a standard feature of iXBRL called Multiple XBRL Target Documents. This allows a single iXBRL report to generate multiple, distinct XBRL instance documents, each tailored for a different purpose or audience. For example, a single iXBRL report could contain XBRL facts intended for two different regulators.
Under the UKSEF approach:
- The default target document: Contains facts submitted to the FCA (e.g. consolidated financial statements), tagged using ESEF Taxonomy.
- The UKFRS target document: Contains facts submitted to Companies House (e.g. SECR disclosures), tagged using the FRC Taxonomy Suite.
To support the UKSEF approach the FRC Taxonomy Suite includes two entry points: 'IFRS-UKSEF' and 'FRS-102-UKSEF'. These entry points are designed to be used in UKSEF reports in place of FRS-102 or IFRS entry points (FRS-101 is not applicable to UKSEF reports).
Readers are referred to the UKSEF Guidance documentation on the FRC Taxonomies website for full information.
2.3. Taxonomy structure
The FRC Taxonomy Suite contains shared components that define elements and relationships for Entity Information, Report Information, Directors'/Strategic Report, Auditor's Report, Accountant's Report, and the Full Detailed Profit and Loss Statement. The FRC Taxonomy Suite also contains a 'core' schema, which defines the elements for disclosure requirements in accounting standards such as IFRS Accounting Standards, FRS 101, FRS 102, and FRS 103.
Applicable entry points extend these shared components, allowing multiple entry points to access and reuse the range of XBRL elements relevant to the specific reporting context.
Figure 1 shows the main components of the taxonomies. It is illustrative and does not show all technical components, files and links. The current list of folders and files in the taxonomies is shown in Appendix F.
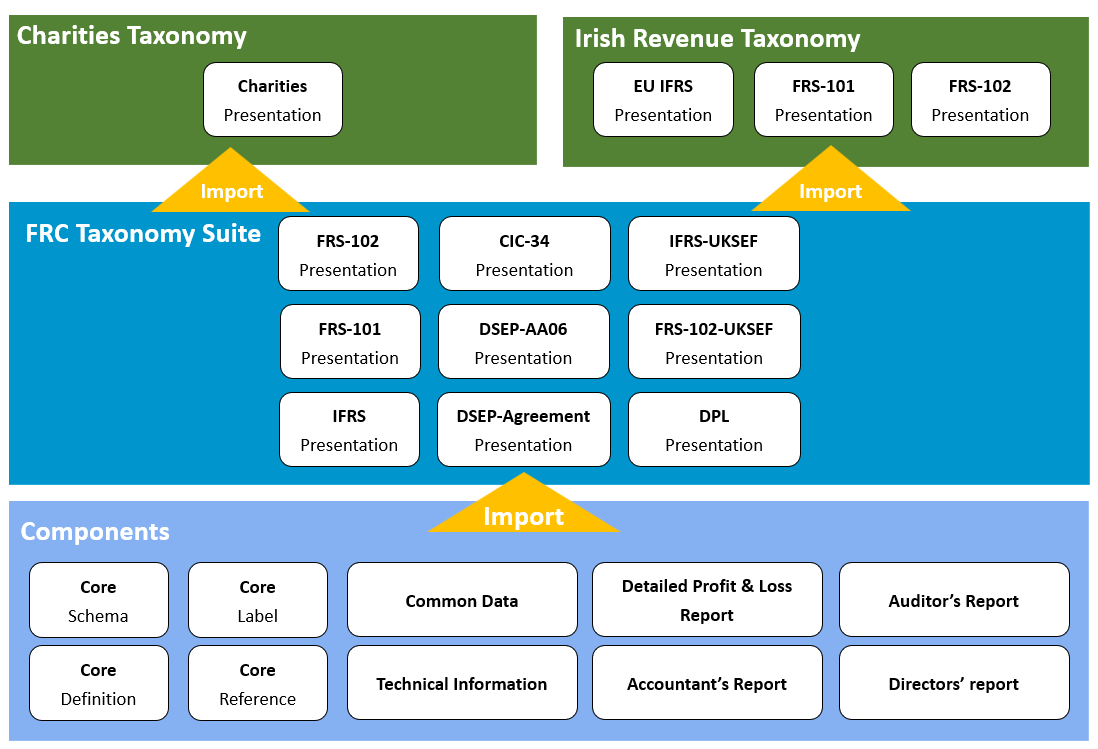
The UK and Irish digital reporting taxonomies structure
The taxonomies also cover specific reporting requirements for sectors with additional reporting requirements. They contain additional sections in relevant entry points to meet the requirements of the banking and finance sector, the extractive industries sector (including mining, oil and gas), the insurance sector and, to a limited extent, investment funds. The banking and finance section includes a full income statement and balance sheet for banks, as these differ in structure from those of non-finance companies. The insurance sections include full profit and loss statements and additional elements for balance sheets, as these differ in structure from those of non-insurance companies. However, other parts of the industry sector sections only show additional elements.
Key Information Document
Users should open a taxonomy in appropriate software through an entry point, which is listed in the taxonomy key information document. An entry point, which is always a schema .xsd file, will automatically import the relevant taxonomy file set. Key information documents published with each taxonomy zip package on the FRC website provide a range of basic information including:
- Name of owner, version date and number.
- Copyright, warranty and related legal information.
- Entry point for the taxonomy (the file through which a taxonomy should be opened in XBRL software).
- Schema location and reference: the entry point which should be used by iXBRL reports based on the taxonomy.
While end-users typically access the taxonomy via third-party software, all users are required to comply with the legal terms and conditions included in the taxonomy package.
3. Taxonomy Design features
3.1. Concept
To ensure every fact in an iXBRL report is machine-readable and unique, XBRL uses metadata. This metadata provides the necessary context to turn a simple fact value, such as "5,000," into a meaningful fact. Every fact in an iXBRL report is uniquely identified by its aspects. They provide the specific information needed to distinguish one fact from another. If any two facts have the same aspects, they are considered duplicates.
A concept is the primary aspect that defines the business meaning of a reported fact (e.g., "Assets" or "Profit"). In technical terms, the concept is an element defined in the taxonomy schema, and each concept possesses a machine-readable name and several attributes.
3.1.1. Element Names
Element names are unique identifiers designed to be read by machines. In the taxonomies, element names are derived from their human-readable standard labels. An example is 'OperatingProfitLoss', which is the name for the element labelled 'Operating profit (loss)'. This design decision serves a practical purpose: it enables technical users, such as data analysts and software developers, to easily read and understand the underlying data in the XBRL files. Ordinary users should never need to be aware of the element names.
The basic conventions followed for the creation of element names are:
- Drop spaces from the standard label and convert to Camel Case, starting with a capital letter.
- Drop all punctuation characters apart from '-' and '.' (hyphen and stop).
- Remove the words: a, the, at, and, of, and is.
By deriving names from the standard label, the data remains intelligible even without the need for specialised taxonomy viewing software, which promotes transparency and efficient debugging.
3.1.2. Namespace
Namespaces are Uniform Resource Identifiers (URIs). These are identifiers that follow the same format as URLs, which are used to locate resources on the internet. This attribute provides a critical mechanism for ensuring global uniqueness and preventing naming conflicts across elements in different taxonomies reflecting different reporting standards. It provides a way to differentiate between concepts that might have the same local name but different underlying definitions (e.g., "Profit" in US GAAP vs. "Profit" in UK GAAP). All the namespaces used in the taxonomies and their purposes are explained in the Appendix H.
3.1.3. Data Type
The data type attribute defines the specific type of data a concept can accept. The taxonomies incorporate data types mandated by both the core XBRL 2.1 specification and the Data Type Registry; where necessary, custom data types are also defined to serve specific reporting requirements. The data types used in the taxonomies are listed in Appendix B.
3.1.4. Period Type
This attribute forces a concept to be reported using a specific period type. All elements carry either an 'Instant' or 'Duration' period type. Concepts defined with 'Instant' period type represent a specific point in time and require a single date. Concepts defined with 'Duration' period type represent a period of time and require both start and end dates to reflect the full reporting interval.
3.1.5. Balance Type
The balance type attribute is used for concepts with a monetary data type. It classifies the expected accounting balance of the concept as either debit or credit. A balance type has been applied using the convention that 'credit' represents an outflow of cash while 'debit' represents an inflow. This is consistent with an increase in cash being a debit.
Balance attributes are not applied to informational disclosures such as ‘Nominal value of shares issued in the period' even though they represent recognized accounting transactions.
3.1.6. Abstract
The abstract attribute identifies whether an element is permitted for tagging; specifically, any element defined as abstract (abstract="true") is restricted from being used to tag a disclosure. Its purpose is to provide organisational structure within the taxonomy's presentation or definition linkbases. In the taxonomies, the heading tags, guidance tags, cross-reference tags, and parent of grouping tags, along with dimensions and their domain members, are defined as abstract elements.
3.1.7. Nillable
The nillable attribute determines whether a concept can explicitly be assigned a null (empty) value in an instance document. To ensure maximum reporting flexibility, the majority of concepts in the taxonomies are configured with nillable="true", allowing preparers to use the xsi:nil="true" attribute to communicate that a specific disclosure is intentionally empty, unavailable, or not applicable. This mechanism serves as a crucial data quality indicator, helping regulators and data consumers distinguish between an omitted disclosure, an explicitly empty data point, and a numerical value of zero. Conversely, if a concept is explicitly set to nillable="false", preparers are structurally prohibited from applying a nil tag, and any attempt to file an empty element will trigger a validation error.
3.1.8. Substitution Group
A substitution group is a technical XML Schema mechanism that defines the underlying property of a taxonomy element. Concepts are assigned to the "xbrli:item" group.
3.2. Dimensions
Dimensions are designed to be used in combination with concepts, allowing for a more granular breakdown of reported facts based on a specific classification. For example, operating profit may be reported for continuing and discontinued operations, for geographic or other segments, or for the company or group. It is not practical to represent all these different forms of operating profit by individual concepts in the taxonomy. Instead, a single concept, 'Operating profit (loss)', is used, while the standard breakdowns are represented by the dimensions.
In practice, dimensions often represent the columns in a financial table, while concepts represent the rows. However, dimensions are not necessarily limited to representing such columns or to use within tables.
Dimensions are used, among other things, to distinguish:
- group or company data
- original and revised data
- continuing and discontinued operations
- classes of equity
- classes of property, plant and equipment
- classes of intangible assets
- classes of provisions
- individual geographic, operating and other segments
- individual subsidiaries, joint-ventures and associates
- restated information, including prior period adjustments
- individual acquisitions or business combinations
- a wide range of data related to financial instruments
- individual pension schemes
- individual directors
Different dimensions may be used simultaneously with a concept. For example, the dimension for continuing and discontinued operations is often used in conjunction with other dimensions.
There are two types of dimensions: Explicit Dimensions, which explicitly define a finite, discrete set of domain members within the taxonomy, and Typed Dimensions, which allow the preparer to define the value for domain members rather than selecting from a predefined list of members.
3.2.1. Explicit Dimensions
Explicit dimensions provide a structured way to categorise data using a domain, which represents the complete set of all possible values. For example, the property, plant and equipment dimension contains 'land and buildings', 'vehicles, plant and machinery' and so forth. These values are known as domain members, and they are used with concepts to provide the specific context needed to qualify a fact and accurately reflect the business meaning of a disclosure.
A default member is a pre-assigned domain member within an explicit dimension domain that is automatically applied to a concept if no specific domain member from the dimension is selected. All default domain members include the word '[default]' in square brackets at the end of their label.
For example, the default member of the PPE classes dimension is 'Total property, plant and equipment'. Any PPE concept that is not used in combination with a specific tangible asset dimension member is thus considered to represent the total across all classes. The defaults for the broadly used group/company and restatements dimensions are 'Company [default]' and 'Currently stated amount [default]', respectively.
The availability of default members is intended to reduce the effort involved in tagging. In practice, many concepts are likely to be reported using defaults, without a need for explicit tagging with a specific domain member. Many defaults represent the total for the dimension, although that is not always the case. Figure 2 shows example of 'Intangible assets generation type' dimension distinguishing internally and externally acquired intangibles, including the default member.
 Figure
- Example of a dimension and its default domain member.
Some dimensions have the default member as 'Not applicable [default]'. This domain member causes the dimension concerned to be ignored, except when a preparer actively uses a domain member from the dimension. It simplifies the design of dimensions and the work of tagging. Like other default members, the 'not applicable' member itself is not used in tagging, and preparers are required to avoid applying it to iXBRL reports.
3.2.2. Typed Dimensions
Typed Dimensions do not contain a closed set of specific, predefined domain members, unlike the explicit dimensions which have been described in preceding sections. Instead, they allow preparers to define custom values that conform to a specified XML data type as their domain members directly within the iXBRL report.
Typed dimensions comprise:
- One analysis dimension. This has the domain type 'types:analysis'. Its label is 'x-Analysis [Dimension]';
- 23 grouping dimensions. These have the domain type 'types:grouping'. Their labels begin with x-, followed by the label of the grouping parent, but without square brackets around grouping. An example is 'x-Individual issue of shares grouping [Dimension]'. There is a separate grouping dimension for each grouping defined in the taxonomy.; and
- DSEP Subsidiaries. These have the domain type 'xs:integer'. Its label is 'DSEP Subsidiaries [Dimension]'.
The domain of all typed dimensions is defined as a positive integer (1, 2, 3, 4 etc.). Their content is thus anonymous. Effectively, typed dimensions provide anonymous domain members that enable a concept to be reused any number of times in a report, provided it is associated with a different typed dimension integer value in each case. The number of domain members they contain is not limited.
Typed dimensions behave identically to explicit dimensions, but they cannot have a default domain member, as they do not have an explicit domain member defined in the taxonomy that could serve as a default. The content of typed dimensions does not require definition in individual Extended Link Roles (ELRs) since they have no explicit members. Their content is defined by their domain.
3.3.UK and Irish digital reporting taxonomies specific features
3.3.1. Heading Tags
Heading tags are identified in the taxonomy by the [heading] suffix at the end of their labels and the custom data type 'types:headingItemType'. These elements are defined as abstract, meaning they cannot be used to tag disclosures in an iXBRL report; instead, their primary use case is to act as titles to organise elements in a logical, human-readable hierarchical presentation view, helping users to navigate complex sections of the taxonomy.
3.3.2. Guidance Tags
Guidance tags are identified in the taxonomy by the [guidance] suffix at the end of their labels and the custom data type 'types:guidanceItemType'. These elements are defined as abstract, meaning they cannot be used to tag disclosures in an iXBRL report; instead, they are positioned at appropriate locations in the presentation tree to assist users in understanding the meaning of specific elements. Their primary use case is to provide reminders on the use of dimensions for identifying certain types of information, as well as providing important pointers on whether and how specific elements should be used. Figure 3 shows example of heading and guidance tags.
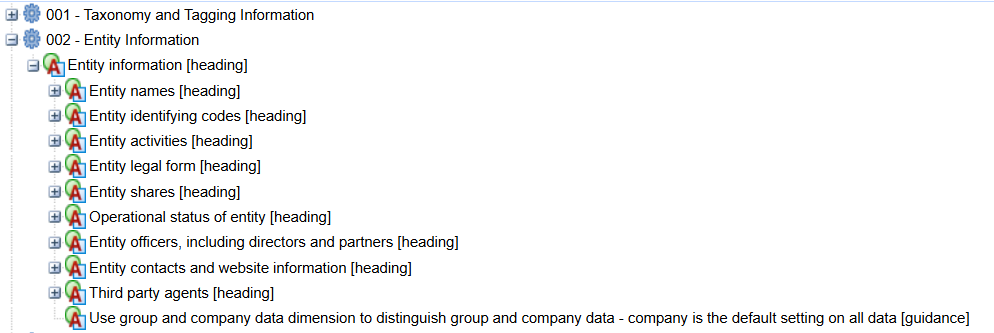 Figure
- Examples of heading and guidance tags
3.3.3. Cross-Reference Tags
Cross-reference tags are defined as abstract elements, meaning they cannot be used to tag disclosures in an iXBRL report; instead, their primary use case is to provide pointers to where related concepts may be found in the taxonomy. They are intended to assist users in navigating efficiently through the taxonomy by highlighting the locations of relevant, interconnected elements.
Cross-reference tags are identified in the taxonomy by the [cross-reference] suffix at the end of their labels and the custom data type 'types:xrefItemType'. These tags are linked to the element to which they point through a custom arcrole 'crossref' in the definition linkbase. The cross-reference tag acts as a parent and the target to which it points is the child of the 'crossref' arcrole. The target may be a heading tag or an ordinary concept, as the example shows.
These relationships are defined in the Extended Link Role (ELR) '9991 - Cross-References'. Figure 4 shows an excerpt of this.
Hierarchical view of cross-references, starting with "9991 - Cross-References". It includes links to sections like "Significant accounting policies", "Banking and finance sector items", "Allowance / provision for impairment losses", "Intangible assets policy", "Financial assets", and "Directors' advances, credits and guarantees", each linked with a cross-reference or heading tag.
Figure
- Excerpt of cross-reference links.
3.3.4. Non-Negative Decimal Tags
Non-negative decimal tags are identified in the taxonomy by the custom data type 'types:nonNegativeDecimalItemType'. These elements are designed to restrict concepts from accepting values less than zero. Their primary use case is to enforce data integrity for concepts where a negative value is logically impossible; for example, if a negative fact value is assigned to the 'Average number of employees during the period' concept, a validation error will occur.
3.3.5. Fixed value Tags
Fixed value tags are identified in the taxonomy by the custom data type 'types:fixedItemType'. They do not contain any value in the iXBRL report and have a predefined fixed value of 'nil'. These concepts have their effect simply by being included in an iXBRL report in combination with an appropriate dimension. Appendix C sets out the fixed value tags and their associated dimensions.
An example is 'Country of formation or incorporation'. To represent the country of incorporation, this tag should be used in combination with the appropriate domain member from the 'Countries and regions' dimension. This ensures unambiguous identification of the country concerned.
Another example is 'Director signing report' in the Directors'/Strategic Report section. This tag should appear in combination with the domain member identifying the director concerned from the 'Entity officers' dimension. (The name of the director is defined separately by the 'Name of entity officer' concept used in combination with the 'Entity officers' dimension.)
These concepts must be entered in the hidden section since they have an empty value and thus cannot be tied to specific text in the readable part of accounts.
3.3.6. Range dimension
Some information may be reported as a range between a high and low value, rather than as a single number. An example is 'Useful life of property, plant and equipment', which is often reported as, say, 10 to 15 years. A 'Range' dimension is therefore used in the taxonomies to handle such cases.
A 'Range' dimension, shown in Figure 5, enables the high and low values of a range to be tagged. The default for the dimension is 'Single Value' and applies automatically unless the domain member for either the high or low value is selected.
 Figure
- Range dimension
This dimension is intended to handle general types of reporting of ranges. It is applied to a small number of numeric concepts where this is justified by disclosure requirements.
3.3.7. Generic dimension domain members
A number of explicit dimensions contain generic domain members to represent classes of information where the precise names of individual domain members are not known in advance. To ensure consistency, these generic domain members are structured by taking the class name and adding a sequence number to identify each individual domain member.
For example, the 'Entity officers' dimension contains generic domain members such as 'Director 1', 'Director 2', and so on. The number of generic domain members defined in applicable dimensions is intended to be sufficient for most purposes. For example, the 'Entity officers' dimension allows up to 40 directors to be identified. Dimensions containing generic domain members may also contain explicit domain members. For example, the 'Entity officers' dimension contains domain members such as 'Chief executive' and other specific roles. A full list of dimensions containing generic domain members, together with their associated name or description concepts, is set out in Appendix D.
By using these generic domain members, individual breakdowns of a class can be reliably tagged and identified. For instance, the concept ‘Name of entity officer' is linked to the 'Entity officers' dimension, which allows multiple directors to be uniquely tagged within the same report.
3.3.8. 'Non-standard' and 'further item' dimension domain members
While the breakdowns of most classes covered by dimensions are predictable, some additional, untypical categories may be used by some companies. To tag such categories, the taxonomies provide a limited number of 'non-standard' or 'further item' domain members along with other domain members within specific explicit dimensions, ensuring that company-specific variations can be fully and accurately tagged. Such domain members should not be used when existing explicit domain members adequately cover the disclosure concerned.
Non-standard domain members can be recognised through their labels, which take the form 'Non-standard XYZ class 1 [component of total XYZ]'. Further item domain members can be recognised through their labels, which take the form ‘Further item XYZ class 1 [component of total XYZ]'.
Figure 6 shows the 'non-standard' dimension domain members from the 'Property, plant and equipment classes' dimension. These are intended to represent unpredictable, specific types of PPE classes.
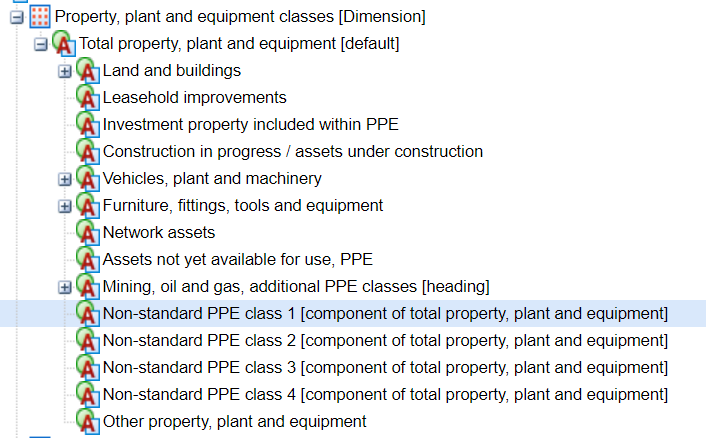 Figure
- PPE classes dimension showing 'non-standard' dimension domain members.
Similarly, Figure 7 shows a set of 'further item' domain members from the 'Finance leases contract type' dimension. These are intended to represent unpredictable, specific types of contracts.
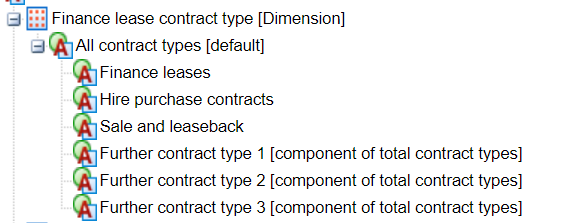 Figure
- Dimension showing 'further item' dimension domain members.
These domain members are purely intended to represent unpredictable categories and should only be used for direct components of the total to which they refer. The total to which a non-standard domain member refers is either shown specifically by its label or is the total for the dimension.
These domain members differ from generic dimension domain members in that they do not represent a general class of items and are not tied to a name or description tag.
3.3.9. Further item concepts and analysis typed dimension
Further item concepts have been included in number of sections of the taxonomies to facilitate the tagging of disclosures for which no specific concept exists. Each further item concept is specific to the section in which it appears and is defined as a component of the total monetary value for that section.
These concepts can be recognised through their labels, which take the form 'Further xyz item [component of abcd]'. Further item concepts are only included in sections where they are likely to be required – they are not included as routine within all sections of the taxonomy.
Labels of further item concepts generally identify the specific total of which the further item concept is a component. However, in cases where items have long labels, the wording ‘[component of corresponding total]' is used instead. The 'corresponding total' refers to the first part of the label. An example is the label: 'Further item of increase (decrease) in amortisation and impairment, intangible assets [component of corresponding total]'. In this case, the total concerned is ‘Increase (decrease) in amortisation and impairment, intangible assets'. In all cases, the corresponding total should be obvious, since it will be the direct parent of the further item concept in the presentation view.
Further item concepts are attached to the analysis typed dimension, 'x-Analysis [Dimension]'. This allows a single further item concept to be repeated multiple times to support complete tagging of the section in which it appears and, where appropriate, to allow the summation of the data in the section to be checked.
Only one such dimension exists in the taxonomies, and it is uniquely defined by its typed domain type which is 'types:analysis'. Only further item concepts are attached to the analysis typed dimension; no other concept is linked to the analysis typed dimension. Further item concepts may thus be recognised by their attachment to a hypercube that contains the analysis dimension.
The analysis typed dimension's domain members are defined as a positive integer; they do not carry inherent meaning. Consumers of iXBRL reports will need to look at the content of the iXBRL report if they wish to see a specific description of the fact concerned.
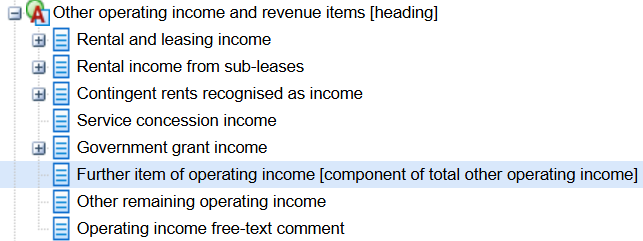
Figure 8 shows an example of a further item concept included under ‘Other operating income':
 Figure
- Example of further item concept
In the example, the label and positioning emphasise that it should only be used for tagging disclosures that are direct components of ‘Other operating income'. If a report includes multiple disclosures that are direct components of total other operating income but cannot be tagged with available concepts, then those disclosures should be tagged with 'Further item of operating income [component of total other operating income]', using a different integer value for the analysis typed dimension that is attached to the concept.
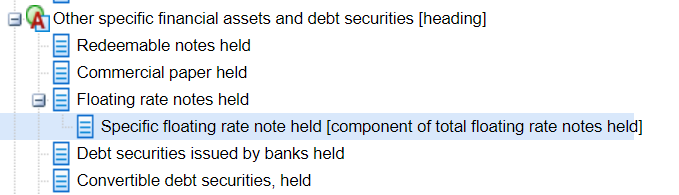
Further item concept labels always take the form 'Further... [component of...]' or, very occasionally, 'Specific... [component of....]'. The 'specific' formulation only occurs where the further item is the only child concept of the total to which it belongs. The concepts with a 'Specific...' label are be used where a report contains breakdowns of a total item, but does not include the total itself, such as the total for floating rate notes, as in this example figure 9.
 Figure
- Further item with 'Specific... [component of....]' label
3.3.10. Grouping Tags
A 'grouping' is used to contain concepts that describe related aspects of a particular piece of information and are expected to be used in combination such as a description of a particular item and its monetary value. Such concepts will only be properly understood when seen in conjunction with one another.
In grouping tags, the parent is an abstract element and always carries the word [grouping] in square brackets at the end of the label. The parent also has a 'groupingItemType' data type. This parent is simply a container and is not used for tagging.
All grouping concepts are attached a grouping typed dimension to enable them to be repeated as required in a report and to identify each occurrence. Each separate grouping has a different grouping typed dimension. However, all grouping typed dimensions have the typed domain type 'types:grouping'; no other dimensions have this typed domain type.
Only grouping concepts are attached to grouping typed dimension; no other concept is linked to the grouping typed dimension. All concepts within a particular grouping may thus be uniquely recognised because:
- All will be attached to a hypercube containing a grouping typed dimension; and
-
All will be linked to the same grouping typed dimension. Concepts in a different grouping will be linked to a different grouping typed dimension. Grouping typed dimension domain members are defined as a positive integers; they do not carry meaning
-
the value is purely to identify the disclosure that match together.
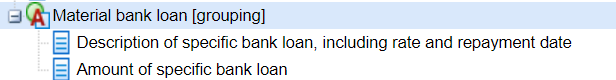
Figure 11 shows the presentation view of the material bank loan grouping concepts and the grouping dimension attached to them.
 Figure
- Material bank loan grouping concepts and dimension attached to them.
In the example, a grouping is used for the concepts that cover 'material bank loan'. This grouping includes concepts that represent (a) 'Description of specific bank loan, including rate and repayment date' and (b) 'Amount of specific bank loan'. These grouping concepts can be reused to tag different occurrences of 'material bank loan' using a different integer value for the 'x-Material bank loan grouping' dimension which is attached to the concept.
3.3.11. Deprecation Policy
When it is necessary to remove some component of a taxonomy, the following process will be followed:
- The label of a deprecated element will be updated to include the word 'deprecated' and the date of deprecation.
- Deprecated elements typically remain available for one taxonomy version before being removed.
- However, if a tag is found to be entirely obsolete, incorrect, or no longer meaningful, it may be removed immediately without a transition period. This change will be communicated via a changelog document attached to the taxonomy release.
- Where the standard or regulation requires deprecated elements to be available for longer than a year, elements will be deprecated when they are no longer relevant, or when the standard or regulation permits their removal.
- Historical taxonomies are available on the FRC Taxonomies website for those who have a legitimate need for them, or for reference.
3.4 Label Linkbase
Since element names are technical, the label linkbase provides human-friendly names. Labels are the natural language expressions (e.g., "Operating profit (loss)") that make the taxonomy elements understandable to users, such as preparers and data consumers.
XBRL labels can be defined in multiple languages and can be of multiple types as explained below. At a technical level, each type of label is differentiated by a label role, which is used to assign a specific meaning to a label.
3.4.1 Standard label
The XBRL specification provides a default label type known as the "Standard Label". All elements have a standard label. Standard label provides a concise name for the element. Standard labels are identified by the role URI http://www.xbrl.org/2003/role/label.
The element name is also derived from the standard label. The wording of labels follows consistent styles; however, it is also intended to reflect common usage, so may vary according to typical usage in accounts. For example, sometimes the word 'costs' is used to represent a cost and sometimes the word 'expense' is used, depending on the terminology commonly used in accounts for the items concerned.
Standard labels in taxonomies are typically longer and more explicit than descriptions of line items in financial reports. For example, a taxonomy label will state ‘Tax on profit or loss on ordinary activities' rather than just 'Tax'.
3.4.2 Terse label
The terse labels are used to provide a concise version of an element's name, identified by the role http://www.xbrl.org/2003/role/terseLabel.
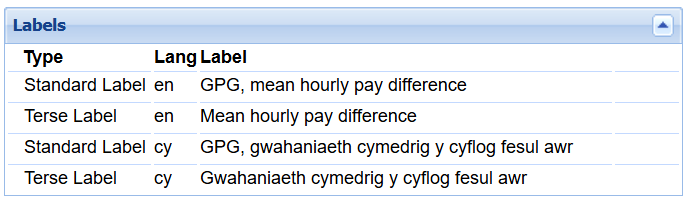
Figure 12 shows standard and terse labels for the concept ‘GPGMeanHourlyPayDifference'.
 Figure
- Standard and terse labels.
3.4.3 Verbose label
The verbose labels are used to provide alternative terminology for a concept, identified by the role http://www.xbrl.org/2003/role/verboseLabel. Their primary use case is to accommodate the varying language required by different accounting standards, such as the specific naming conventions used under IFRS Accounting Standards versus FRS 102.
Figure 13 shows standard and verbose labels for the concept ‘RetirementBenefitObligationsSurplus'.
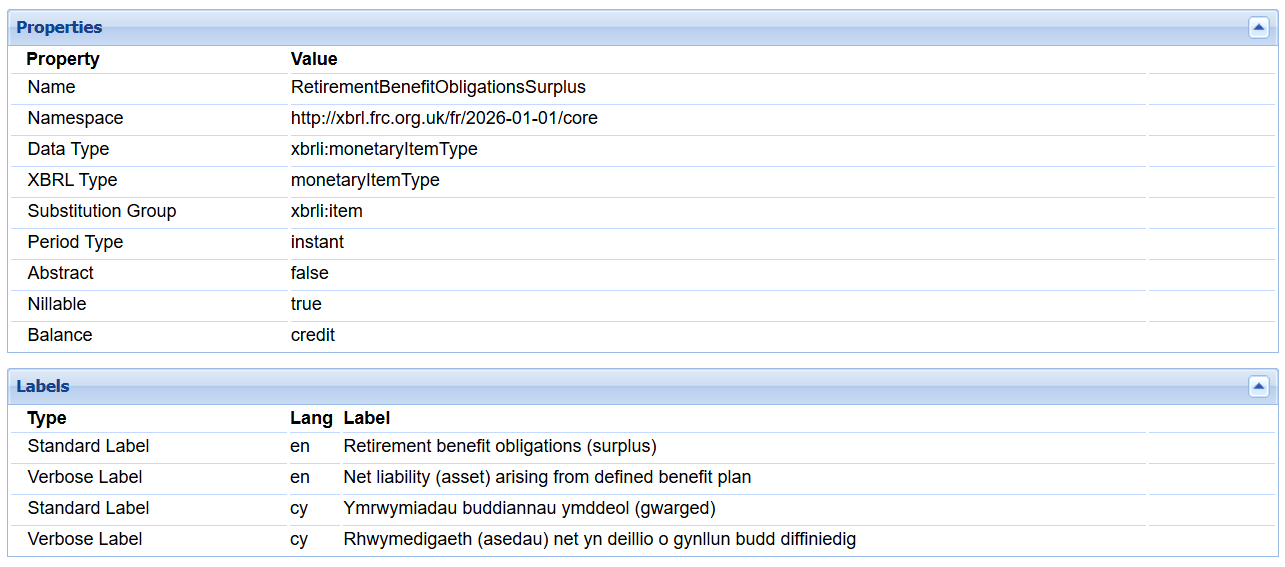 Figure
- Standard and verbose labels.
3.4.4 Documentation label
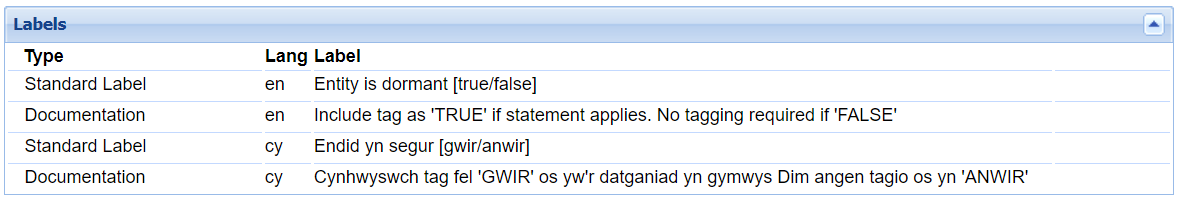
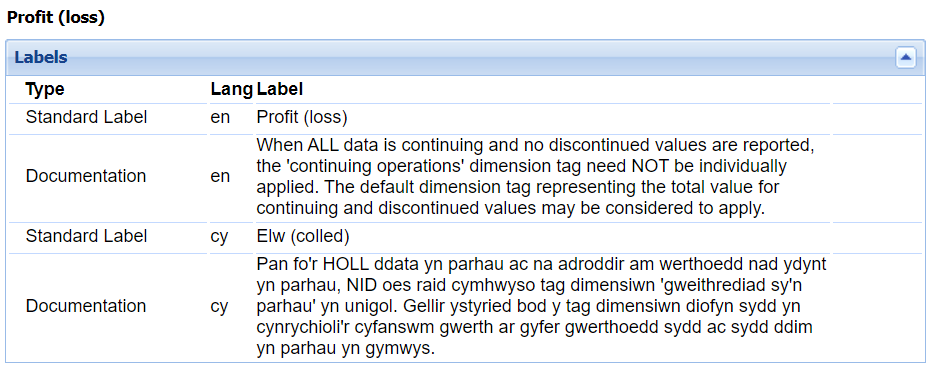
The documentation labels are used to provide additional guidance on how the element should be interpreted, identified by the role http://www.xbrl.org/2003/role/documentation. It is only used where such guidance is necessary. The use of documentation labels has been restricted to concepts; they have not been applied to abstract elements and dimension domain members as this would be likely to overcomplicate user interface displays.
Figure 14 shows examples of documentation labels.
 Figure
- The documentation labels.
3.4.5 Multilingual label
XBRL supports multilingual taxonomies by allowing labels to be defined in multiple languages. When labels in multiple languages are defined, the software used to display an iXBRL report or taxonomy can allow the reader to view labels in their preferred language. From the 2022 version onwards, the FRC Taxonomy Suite and the Charities Taxonomy include a complete set of Welsh labels in addition to English, enabling Welsh accounts preparers and taxonomy browsers to see and understand the contents of the taxonomies in their native tongue (if enabled by their taxonomy-aware software).
3.4.6 Preferred label mechanism
The taxonomies are designed to show different labels for a particular element based on entry point. For example, the term 'Retirement benefit obligations' under FRS 102 is equivalent to the term 'Net liability from defined benefit plan' under FRS 101 and IFRS Accounting Standards. These items are represented by the same concept ‘RetirementBenefitObligationsSurplus' but are presented with different labels depending on the entry point. The standard label for the concept, 'Retirement benefit obligations (surplus)', appears in the FRS-102 entry point presentation view. The verbose label, 'Net liability (asset) arising from defined benefit plan', appears in the presentation views for FRS-101 and IFRS entry points.
Figure 15 shows different displays for the concept 'RetirementBenefitObligationsSurplus' in the presentation view of the FRS-101 and FRS-102 entry points.
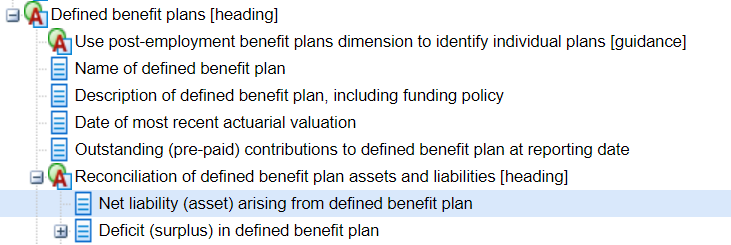
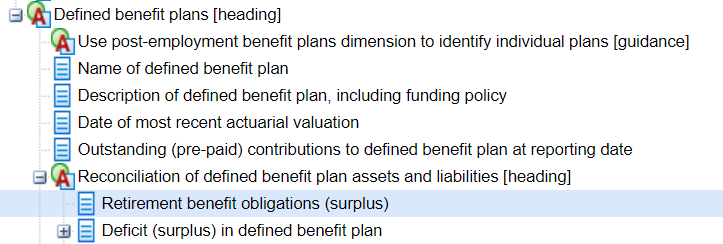 Figure
- Different displays of the concept ‘RetirementBenefitObligationsSurplus' under FRS-101 entry point (top) and FRS-102 entry point (below).
A taxonomy element can be assigned multiple labels of different types. The XBRL ‘Preferred label' mechanism is used to identify which label to display in the presentation view. This ensures the label a user sees is appropriate for the relevant standard and position of the element.
When the verbose label is preferred, this is represented in the presentation linkbase by "preferredLabel=http://www.xbrl.org/2003/role/verboseLabel".
When the terse label is preferred, this is represented in the presentation linkbase by "preferredLabel= http://www.xbrl.org/2003/role/terseLabel".
3.5 Presentation Linkbase
The presentation view is a crucial aspect of the taxonomy, as it dictates how users navigate and interact with elements. This is achieved through the presentation linkbase using parent-child relationships that organise the elements in a hierarchical view. Technically, the presentation linkbase uses the parent-child presentation arcrole.
The basic view of the taxonomy represented by the presentation linkbase shows:
- Concepts arranged in a structure that helps make their meaning and intended application clear to users;
- Guidance and cross-reference tags that are relevant to the section in which they appear; and
- Dimension and domain members arranged in a structure that makes their meaning clear to users.
3.5.1 Presentation view of concepts
Concepts are organised in separate sections and are presented in the same format as the financial reports they typically represent. They mirror the basic structure of accounts, with primary financial statements followed by notes and detailed disclosures. Technically, the presentation view is divided into sections by ELRs. Figure 16 shows the basic structure of the FRS-102 entry point.
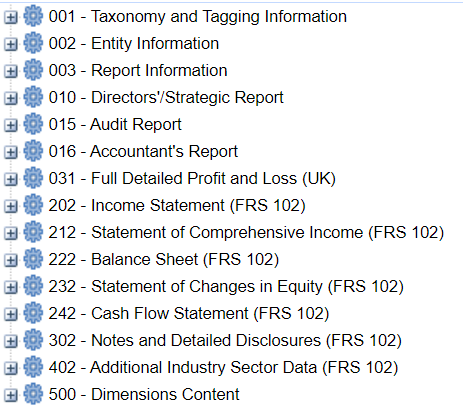 Figure
- The top-level structure of the FRS-102 entry point of the FRC Taxonomy Suite.
The XBRL specification does not determine a means of ordering ELRs. However, by convention, the taxonomies assume that ELRs will be ordered for presentation by the number that begins the definition of the ELR. This is the number shown above at the start of each ELR title. The value of the number used in an ELR definition has no significance in itself – the number is used purely for ordering and identification purposes.
While organising the elements into separate sections helps in locating specific elements, this structure is further enhanced and supplemented by the strategic inclusion of heading tags and guidance tags wherever necessary within the presentation hierarchy. These tags provide essential organisational context and practical explanations that guide the user through the presentation view of elements. Figure 17 shows the presentation of part of the FRS 101 provisions section, including heading and guidance tags. This provides a typical view of the arrangement of concepts in a presentation hierarchy.
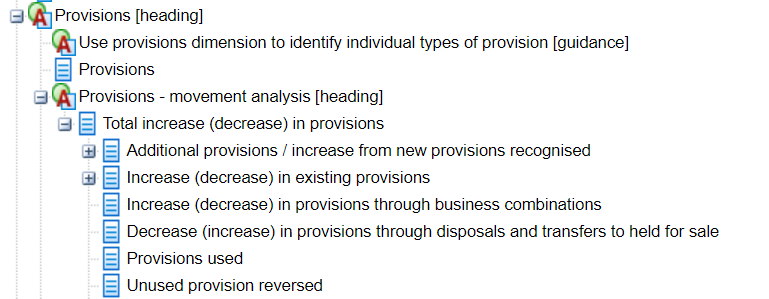 Figure
- Presentation view with Heading and Guidance tags
The identification of concepts within the taxonomy relies heavily on their specific positioning within this presentation view. For example, a parent heading like "Net cash flows from (used in) operating activities" clarifies the meaning and appropriate use of the concepts grouped underneath it. This method of identification through structural placement is designed to minimise ambiguity and ensure that the correct accounting meaning is consistently applied by all users, promoting high-quality and consistent digital reporting. Some concepts may appear in multiple places in the presentation view because they may typically be reported in different positions in accounts.
The presentation view of the taxonomy is intended purely to help users locate and identify concepts in the taxonomy. It does not define how items should be presented in accounts filed in iXBRL - that is determined by the preparer. Companies are not expected to adjust the presentation of their accounts to fit the taxonomies. Given the wide variety of presentations of accounts that entities may use, the presentation view is very unlikely to match exactly the organisation of any individual set of accounts.
3.5.2 Presentation view of dimensions
The complete list of explicit dimensions and their domain members are organised in a separate section '500 – Dimensions Content' of the hierarchical presentation view using the presentation linkbase.
Each explicit dimension is defined in its own Extended Link Role (ELR). The definition includes the dimension element itself, domain members and the default member, if any. The dimension ELRs are numbered from 6001 onwards. There are gaps in the ELR numbering to allow the addition of other dimensions by subject group in the future, if required.
Arcroles used in the definition of explicit dimension content are ‘dimension-domain', 'domain-member' and 'dimension-default'. The dimension-domain arcrole establishes the relationship between a dimension and its domain. The domain-member arcrole defines the hierarchical relationship between a domain and its individual members, or between one member and another (parent-child). The dimension-default arcrole identifies the specific domain member that serves as the default value for the dimension.
The section '500 – Dimensions Content' in the presentation linkbase shows the content of explicit dimensions and their domain members. It does not show how dimensions may be used in combination with concepts.
3.6 Definition Linkbase
The display of available dimensions for any concept is driven by the definition linkbase. The hypercube acts as a central point within this linkbase.
3.6.1 Hypercube
A hypercube is essentially a container that links a specific concept to the dimensions that can be used together when reporting a fact. Hypercubes are abstract elements and have the substitution group 'xbrldt:hypercubeltem'. Their labels end in the term '[Hypercube]'. Each occurrence of a hypercube is defined in its own ELR in the definition linkbase. Their main numbering sequence begins at
- The numbering of ELRs is purely for convenient identification and ordering, in the same way as for the presentation linkbase. It has no other significance.
3.6.2 Hypercube and dimensions
Each occurrence of a hypercube contains a set of dimensions as children. Hypercubes are linked to dimensions by the 'hypercube-dimension' arcrole. Explicit dimensions in a hypercube are tied to the dimension ELRs in which their content is defined by the 'target-role' attribute. Typed dimensions just appear as children without any target role attached.
Some hypercubes appear in more than one ELR, with adjusted content in each case to cover analysis typed dimension and grouping typed dimensions, as described below. By convention, the number of the separate ELR has the same root as the ordinary occurrence ELR, but with an added integer. This is purely for convenient identification and for suitable ordering within software; it has no other significance.
While most hypercubes are limited to a single occurrence, the 'Basic hypercube', which contains the dimensions for group and company restatements and original and revised data, has nine separate variations, including an analysis hypercube and eight distinct grouping hypercubes.
Figure 18 shows a hypercube along with an analysis hypercube and a grouping hypercube.
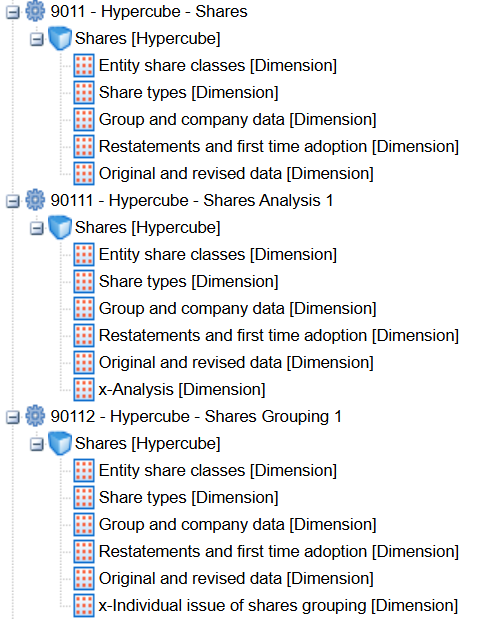 Figure
- Shares hypercube, Shares analysis hypercube, and Shares grouping hypercube
In this example, '9011 Shares' hypercube includes only explicit dimensions to be used for information on shares, including dividends.
The '90111 Shares Analysis 1' hypercube additionally includes an analysis typed dimension to be used for further item concepts related to shares. This enables shares' further item concepts to be combined with the explicit dimension as ordinary share concepts, and the appropriate analysis typed dimension. This occurrence of the Shares hypercube is contained in a separate ELR since it has different children from the ordinary occurrence.
The '90112 Shares Grouping 1' hypercube additionally includes a grouping dimension to be used for the grouping concepts. This enables grouping concepts contained in the 'individual issue of shares' grouping to be combined with the explicit dimension as ordinary share concepts and the appropriate grouping typed dimension. This occurrence of the Shares hypercube is contained in a separate ELR since it has different children from the ordinary occurrence.
Grouping concepts are only attached to a single hypercube that contains the corresponding grouping typed dimension. Each grouping has a different grouping typed dimension, so several occurrences of hypercubes may exist for areas that include a number of groupings. Each hypercube occurrence will contain a single grouping typed dimension and each will be in its own ELR. Figure 19 shows the two grouping occurrences for the Entity Officers hypercube.
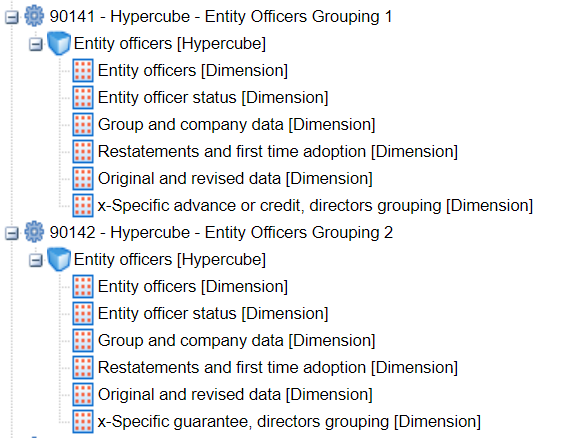 Figure
- Two entity officers grouping hypercubes.
Further item concepts are only attached to the hypercubes appropriate for their subject matter that contain the analysis typed dimension. Unlike grouping concepts, a further item concepts may be attached to more than one hypercube. In particular, financial instrument further item concepts are typically attached to both the basic version of the financial instrument hypercube and the full version of the hypercube. For example, the further item concept 'Further item of financial assets [component of total financial assets]' is attached to both the 'Financial assets – basic' hypercube and the 'Financial assets – full' hypercube. However, the majority of further item concepts are attached to a single hypercube.
3.6.3 Hypercube and concepts
An ELR containing a hypercube also contains the concepts linked to that occurrence of the hypercube through an ultimate parent element 'primary items'. These parent items are abstract elements and have labels ending with '[Primary items]'.
The same parent item is used with each hypercube in the ELRs in which the hypercube occurs. Effectively, the parent and hypercube form a pair and always appear together.
Concepts that may be used with an occurrence of a hypercube are attached as children of the 'primary items' parent in the ELR containing the hypercube. Concepts are attached to the primary items parent using the domain-member arcrole.
Figure 20 shows an example of the top-level structure for the 'Shares' hypercube.
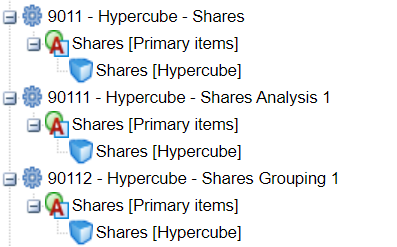 Figure
- Top-level structure for the 'Shares' hypercube. In this example, shares' further item concepts (for e.g., Further item of increase (decrease) in number of treasury shares [component of total change in number of treasury shares]) are attached as children of the 'Shares [Primary items]' tag in the ELR '90111
- Hypercube - Shares Analysis 1'.
In the taxonomies, parent items are attached to hypercubes using the 'all' arcrole. (The taxonomies do not use the 'notAll' role which may be used in some complex dimensional constructions.)
All hypercubes are defined as closed. Effectively, this means that the relationship between primary items and dimensions is fixed by the taxonomy. A primary item cannot be reported with a dimension member to which it is not linked in a hypercube.
By convention, the 'all' arc is defined using the 'segment' element of context. The scenario element of context is not used. This is purely a matter of technical convention and does not alter the functionality of dimensions. (One or other part of context has to be chosen: segment was chosen for consistency with taxonomies elsewhere.)
All usable concepts are attached to at least one hypercube. Concepts may be attached to a number of hypercubes, reflecting the different ways in which they may be reported. However, grouping concepts are only attached to one hypercube in one ELR, reflecting their specific use.
3.6.4 Prohibition of links in definition linkbase
The XBRL specification allows links in linkbases to be prohibited. This is useful in an extension taxonomy that modifies an imported taxonomy.
This is used extensively in the Charities and Irish Taxonomies, while FRC taxonomy makes limited use of prohibition. For example, the FRS-102 entry point definition linkbase prohibits a small number of domain-member links in the core definition linkbase, effectively removing from use a small number of dimension domain members that are not appropriate for FRS 102 accounts.
3.7 Reference Linkbase
The elements have references to accounting standards and/or local laws that turn a raw value into usable financial information. References are helpful in identifying the meaning of an element and explaining its use as they link specific elements to the authoritative document that defines the disclosure requirements.
Taxonomy elements typically carry one or more accounting references. These citations state the relevant publication (e.g., FRS 102) and the specific section or paragraph number that defines the disclosure requirement. These references are essential for preparers (confirming meaning and compliance), and reporting software should make this information easily accessible for efficient manual tagging and verification.
Figure 21 shows an example of a reference.
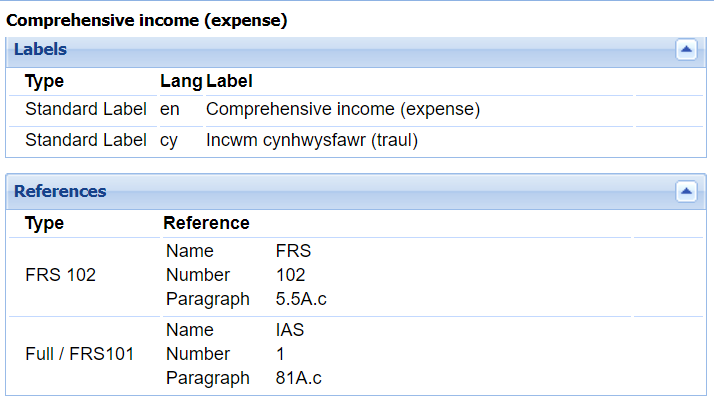 Figure
- References for concept for comprehensive income (expense). In this display, 'type' shows the 'reference role' identifying the standard to which the reference applies.
References in the taxonomies adhere to the following practices:
- All accounting concepts carry one or more references to accounting standards or legislation.
- References have a 'reference role' identifying the standard(s) or legislation to which they relate, such as FRS 102. They contain the name of the publication identified by acronym (such as FRS for Financial Reporting Standard, CA for Companies Act) and the numbers of the publication, schedule, paragraph or similar information which define the concept.
- IFRS and FRS 101 accounting content has references to the IFRS Accounting Standards.
- FRS 102 accounting content has references to FRS 102.
- FRS 103 accounting content has references to FRS 103 and the Implementation Guidance to accompany FRS 103.
- Charities SORP content has references from Charities SORP and FRS 102.
- Auditor's report content has references to the ISA (UK), ISA (Ireland).
- Taxonomies also include references to the Companies Act, Charities Act, CIC 34 and other official publications, where appropriate.
- References related to different standards are available across all entry points. (Technically, they are contained in reference linkbases which are common to all taxonomies.) An FRS-102 entry point user can thus see the references for IFRS Accounting Standards and FRS 101, as well as FRS 102. This comprehensive reference information should benefit users by providing complete information on the authority for a concept.
- All references are to specific sections of official standards. We have avoided the use of generalised terms within references such as 'derived practice' or 'common practice'.
- Dimensions and domain members do not in general carry references since their broad use means that specific references to individual paragraphs in standards are not appropriate. However, country, currency and language dimensions carry International Standards Organisation (ISO) references to confirm the identification of members concerned.
- References to IFRS Accounting Standards, FRS 101, FRS 102 and FRS 103 use only 'Name', 'Number' and 'Paragraph' reference parts. References to the Companies Act and similar publications may use other parts as required, such as ‘Schedule' and 'Year'. 'Paragraph' is the most detailed 'reference part' used for textual standards in the taxonomies. The taxonomies do not use reference parts representing sub-divisions of paragraph such as clause or sub-clause. Such subdivisions are represented by components within the paragraph reference, with each component separated by a stop (.). An example is 'para: 3.c.ii'. Brackets are not used to separate components. This approach provides simplicity of presentation. It also avoids difficulties in determining consistently what is a sub-para, clause, sub-clause and the like, since standards do not necessarily explicitly define such distinctions. Reference parts which reflect official, higher-level sub-divisions in UK Acts, such as 'Schedule', are used.
- Where a reference relates to a range of paragraphs or sub-divisions of paragraphs, the range is shown within a single reference field. For example, a reference relating to paras 31, 32 and 33, is shown as 31-33 in the paragraph field. This is not shown as three separate individual references to para 31, para 32 and para 33. This applies even if the sections are not contiguous. For example, a reference to para 32, clauses (a) and (c) is shown as 'para: 32.a,c', not as separate references to 'para: 32.a' and 'para: 32.c'. References to a range use a dash (-) as separator. References to closely tied, non-contiguous items use a comma as separator. This approach is intended to simplify the presentation and viewing of references by users. Clearly, if two or more references are genuinely separate and relate to entirely different sections of a standard or to different standards, then separate references are used.
3.8 Other technical information
3.8.1 Arcroles
The list of arcroles currently used in the taxonomies is shown in Appendix E.
3.8.1 Roles
The list of roles currently used in the taxonomies is shown in Appendix F.
4. Implementation Guidance for Preparers and Software Developers
This section provides clear guidance for preparers to follow during the tagging process, while simultaneously providing guidance for software developers to build compliant applications that effectively support preparers. The rules stated below refer to 'tag' (element) in the singular, but they must also be taken to mean combinations of tags, covering both the line item tag (concept) and associated dimension tags (dimension and domain members), where appropriate.
Note on Regulatory Scope: These technical principles define the structural and architectural logic of the taxonomies based on international XBRL standards. While this guide establishes the technical rules for applying the tags, the legal mandates and specific filing rules (such as permitted taxonomy versions, exemptions, and electronic formatting validation) are governed independently by the respective receiving authorities (including Companies House, HMRC, and Irish Revenue). Preparers must verify and adhere to the specific submission requirements of the relevant receiving authority.
Conventions used in this guide When stating rules, this guide uses the following conventions to indicate requirement levels, based on RFC2119 published by the Internet Engineering Task Force (IETF) organisation.
MUST: This word, or the terms "REQUIRED" or "SHALL", means that the definition is an absolute requirement.
MUST NOT: This phrase, or the phrase "SHALL NOT", means that the definition is an absolute prohibition.
SHOULD: This word, or the adjective "RECOMMENDED", means that there may be valid reasons in certain circumstances to ignore a particular item, but the full implications must be understood and carefully weighed before choosing such a course.
SHOULD NOT: This phrase, or the phrase "NOT RECOMMENDED", means that there may be valid reasons in certain circumstances when the particular behaviour is acceptable, but the full implications should be understood and carefully weighed before adopting it.
MAY: This word, or the adjective "OPTIONAL", means that an item is truly optional.
Rules Main rules set out in the document are highlighted using the following convention:
RULE
Text of rule
Rules are identified by the numbering of the section in which they appear.
4.1 Choice of taxonomy version and entry point
4.1.1 RULE
Preparers MUST use the appropriate entry point from the taxonomy and its appropriate version that models the underlying accounting standards and filing requirements used in the preparation of their accounts.
The taxonomies are updated annually to reflect amendments in the standards and practical usage feedback. Preparers must select the specific taxonomy version that models the underlying accounting standards used in the preparation of their accounts. Using older taxonomy versions that lack the necessary elements to digitally represent required disclosures will result in incomplete tagging. The specific taxonomy versions that preparers can use, including dates for adoption, are governed by the requirements and guidance of the relevant data collectors, such as HMRC, Companies House, and Irish Revenue.
Preparers must use the appropriate entry point from the taxonomy. For example, companies reporting under FRS 102 must use the FRS-102 entry point. The "001 - Taxonomy and Tagging information" section in the presentation tree of the taxonomy provides information on the available entry points in the taxonomy.
Some consolidated reports may contain statements reported under different standards, for example group data reported under IFRS Accounting Standards and company data under FRS 101. Such reports may be linked to multiple entry points, with the group data tagged using the IFRS entry point and the company data tagged using the FRS-101 entry point.
Software should make it clear to preparers within the applications which versions of the taxonomy are available for use, and which version is being used at any given time.
4.2 Scope of tagging
4.2.1 RULE
All disclosures in a report MUST be tagged with an appropriate concept with dimensional breakdown if a suitable element exists in the relevant entry point of the taxonomy.
In simplest terms, the XBRL tagging of a report is achieved by matching specific disclosures within a report to their corresponding concepts, including any necessary dimension(s). The disclosure concerned may consist of a monetary value, an ordinary number, a date, a section of text or some other standard type of data.
For example, if a financial statement contains the line item ‘Operating profit £300,000′ then the value 300,000 should be tagged with the concept whose label is 'Operating profit (loss)'. Note that the concept is only applied to the financial value; the description of the line item in the human-readable accounts remains untagged and is handled purely as text. Some textual disclosures in reports have associated concepts and should be tagged accordingly. This includes the text of specific declarations, policies and descriptions.
4.3 Display of concepts and dimensions information
As explained in section 3.5.1, concepts are organised in separate sections using ELRs in presentation hierarchy. Software should convey the meaning carried in the presentation linkbase hierarchy to users. Whether this is done by reproducing the structure of the presentation linkbase or by other suitable means is up to the developer. If developers choose to display available elements to users in a different form from the presentation linkbase hierarchy (for example, in an alternative hierarchy or an alphabetical list), then they must find means of conveying the meaning carried by the original presentation hierarchy. They must also ensure that relevant information provided by heading, grouping, guidance, and cross-reference tags is not lost to users.
Taxonomy displays must provide users with all relevant information about the concepts to support their correct use and interpretation. While some required information may vary based on the nature and purpose of the software applications, certain data is likely to be helpful to users in almost all circumstances.
4.3.1 RULE
Software displaying the taxonomy MUST include all key information likely to be helpful to users in selecting and understanding the meaning of concepts. Typically, this will require clear display of the following information for individual concepts:
- Data type;
- Balance type;
- Period type;
- Abstract / non-abstract;
- Label based on preferred label mechanism
- Documentation label;
- References; and
- Linked dimensions.
Displays SHOULD include all features likely to be helpful to users in recognising and locating concepts. This includes appropriate presentation of heading tags, guidance tags, and linking to tags referenced by cross-reference tags.
As described in section 2.3, instead of defining concepts multiple times within each entry point, the FRC Taxonomy Suite includes a 'core' and other common schemas, which define the concepts that can be reused in multiple entry points. Each individual taxonomy and entry point extends the appropriate common schemas to reuse the concepts. While the entry point excludes irrelevant concepts from the common schemas in its presentation linkbase, these concepts remain technically accessible by tagging software during report preparation, as they are included in the overall Discoverable Taxonomy Set (DTS).
4.3.2 RULE
Software MUST ensure that concepts exposed by the presentation linkbase of a relevant entry-point are available for tagging, ensuring concepts unique to other entry-points are not presented.
In displaying the dimensions that can be used with a concept, software must make clear to users:
- the available hypercubes for any concept;
- the dimensions in the hypercube; and
- the domain members within each dimension.
4.3.3 RULE
Software MUST make clear to users the available hypercube(s) for each concept and enable efficient choice between them, for example by displaying the hypercube name or a suitable description and enabling expansion to show hypercube dimensions.
Software SHOULD order displays of available hypercubes by the number of the hypercube Extended Link Role (ELR).
Most concepts are attached to a single hypercube that determines the set of dimensions for that concept. However, some concepts are attached to more than one hypercube, reflecting the different ways that the concept may be reported.
Typically, the lower the ELR number of a hypercube for a particular concept, the more commonly the hypercube is likely to be used. (This may not always be the case, but the ELR number provides better ordering than alphabetical or other similar methods.)
For example, the concept 'Equity' is attached to two hypercubes – one is the standard '9240 Equity and SOCI [Hypercube]' which enables items to be reported for different equity classes and the other is the '9243 Equity and SOCI - segments [Hypercube]' which enables certain equity and comprehensive income items to be reported for different segments. Preparers will generally require the standard hypercube, but will occasionally require the segments hypercube, which contains more dimensions. Figure 22 shows the two hypercubes.
Figure
- The two available hypercubes for the 'Equity' concept. The lower hypercube (9240) will normally be used, but the upper (9243) will be required for segment information
Some other concepts, particularly for financial instruments, are attached to several hypercubes. The large number of dimensions available for financial instruments is divided into different hypercubes to make tagging more manageable. Preparers select the dimensions required from the single hypercube that meets their purpose. There are 'basic' financial assets and liabilities hypercubes which contain the most commonly used financial instrument dimensions and 'full' financial assets and liabilities hypercubes which contain all the financial instrument dimensions that may be required for more complex analyses. In addition, segment and other hypercubes may be required for certain financial instrument concepts.
For example, the 'Investments' concept is attached to four hypercubes:
- Financial assets - basic.
- Financial assets - full.
- Financial assets – segments.
- Investment movements. This hypercube contains dimensions that enable movements in fixed asset investments to be tagged.
Within hypercubes, the available dimensions and domain members must also be displayed clearly to users. As with the presentation linkbase, the structure of dimension and domain members in the definition linkbase has been chosen to help clarify their meaning and intended use. Some dimensions include heading items to organise dimension domain members and some also include guidance tags. These should be retained in displays to help users navigate through the dimension domain members.
In displaying available dimensions and domain members, software must follow the XBRL rules that determine the correct use of dimensions with concepts. The definition linkbase does not permit concepts to be used with inappropriate dimensions. Attempts to do so will lead to an invalid iXBRL report.
4.3.4 RULE
Software MUST clearly present the available dimensions and domain members within a hypercube that may be used in combination with a specific concept, while facilitating an efficient selection process between them. Displays MUST NOT muddle together the content of separate hypercubes or encourage invalid uses or combinations of dimensions with concepts.
Software SHOULD show dimensions and domain members in the hierarchy and ordering defined in the definition linkbase.
Failure to represent these rules and associations clearly and accurately may lead to incorrect tagging and to invalid iXBRL reports.
The form of display of dimension information and concepts is for software developers to determine. For example, dimensions relevant to a particular concept could be displayed in either pop-up or fixed windows in tagging software. The rules set out above are purely concerned with the scope and logic of the dimensional information conveyed to the user.
As described in section 3.6.4, taxonomies uses prohibition of links in definition linkbase.
4.3.5 RULE
Software MUST correctly implement prohibitions in linkbases. Failure to do so is likely to lead to incorrect tagging and invalid XBRL report.
4.4 Choice of tags
In general, the appropriate concept for a disclosure should be relatively obvious once the concept is located in the presentation hierarchy. For example, an item in an FRS 102 income statement described by a company as 'Profit prior to tax' and appearing prior to the tax charge on ordinary activities can be matched against an element in that position in the FRS 102 taxonomy labelled 'Profit (loss) on ordinary activities before tax'. The label used for an item in a taxonomy may not exactly match the description used by a company.
4.4.1 RULE
A disclosure MUST be tagged with the closest available concept, based on its label, position in the presentation view, accounting reference, data type, period type, and other taxonomy information PROVIDED that the use of the concept to represent the disclosure does not introduce a material distortion in the meaning of the business report. The closest appropriate dimension domain member MUST also be applied in order accurately to reflect the meaning of a fact disclosed.
The position of a concept in the presentation view of a taxonomy is a strong clue to its meaning. For example, a concept listed in the taxonomy under ‘Operating costs' is clearly an expense item and not an asset.
However, a concept's position in a presentation view will not necessarily match that of the corresponding item in a company's report. Companies vary significantly in where they choose to place items in their reports. The presentation view in the taxonomy provides guidance on meaning but it is NOT definitional. For example, concepts used to tag disclosures in the primary statements section may be used to tag disclosures in the notes of a company report and vice versa. Companies may thus find suitable concepts in locations which do not match the particular presentation of their accounts.
Different reporting entities, or a single entity across various periods, may use differing terminology for the same disclosure. Preparers of iXBRL reports must look past variations in terminology, identify the core meaning of the disclosure, and tag accordingly.
The basic rule on matching allows some latitude in the application of concepts to disclosure in reports. It seeks the best available match. It recognises that the limited number of tags in a taxonomy cannot represent all the subtlety of meaning which a company may impart through the descriptions and details of formatting which it employs in its financial statements. The latter may be reproduced using iXBRL, while tagging is used to convey the general meaning of the item concerned.
Nevertheless, concepts should not be 'stretched' in their meaning in order to tag a disclosure. This would undermine the consistency of tagging across companies.
It is the responsibility of the preparer to make a reasonable judgement on the application of concepts in its financial reports.
4.5 No tag available
4.5.1 RULE
If the chosen entry point lacks a suitable tag for a specific disclosure, the preparer MUST leave that disclosure untagged in the iXBRL report.
The taxonomies are intended to support comprehensive tagging of the accounts of companies in the industry sectors that they cover. However, disclosures should only be tagged if suitable elements are available in the relevant entry point of the taxonomy. Elements may not exist for certain disclosures that is specific to certain companies or sectors and/or is not suitable for comparison or analysis by software.
4.6 Alternative tags
4.6.1 RULE
When alternative tags, of different levels of granularity, in a taxonomy both match a disclosure in a report, preparers of iXBRL reports MUST choose the tag that best represents the intended meaning and level of granularity of the disclosure. In doing so, they MUST abide by the following rules:
- If the disclosure is intended to represent a broad total, then the concept which represents such a total MUST be used. In particular, broad total concepts SHOULD be used to represent data in primary statements of accounts.
- If the disclosure is intended to represent a detailed breakdown, then the concept which represents that level of breakdown MUST be used. In general, detailed or granular concepts SHOULD be used to represent data presented in notes to the accounts.
Alternative tags with different degrees of generality will often be available to match an item in a business report. The positioning of the tags within a taxonomy – and thus the level of detail they are intended to represent – will indicate which should be used.
The aim of this rule is to ensure that tags for broad totals are not missing from an iXBRL report, even if a company uses a detailed description for an item in a primary statement. It is also intended to ensure that detailed information in the notes to the accounts is tagged to the appropriate level of detail.
4.7 Unique application of tags
4.7.1 RULE
The combination of a concept and its context (entity, period, and dimensions) MUST be applied to a unique value; the same concept MUST NOT be assigned to conflicting data values within the exact same context.
The same concept MAY be reused across a report only when applied with a different context, such as a different reporting period or a distinct dimensional breakdown.
This rule ensures that different values for the same disclosure do not appear in different places within a report. The same accounting line item may appear both in a primary statement and in a note to the accounts. Both occurrences must be tagged with the same concept and same context. For example, if the concept 'Operating profit (loss)' is assigned to a value of £1 million for a specific period and company, it must not also be assigned to a value of £1.5 million for the same period and company.
4.8 Tagging of multiple occurrences of data items
4.8.1 RULE
Where a specific disclosure is reported multiple times in a financial section of a report then all occurrences of that disclosure MUST be tagged consistently with the same concept and the same context. This does not apply to administrative data items.
This rule ensures that data in financial reports is filed consistently and enables a range of basic validity checks. It helps to ensure that different numbers for the same thing do not appear in different places within a report. For example, the same accounting line item may appear both in a primary statement and in a note to the accounts. Both occurrences must be tagged.
Administrative data items that appear on nearly every page of a report, such as the official Company Name, should only be tagged once. Preparers MUST NOT tag every casual mention of such information throughout the report.
Disclosures in the Directors' and Auditors' Reports should only be tagged if specific concept exist within the Directors' and Auditors' Report sections of the taxonomy. Disclosures on turnover or profit in the Directors' Report need not be tagged, since it is assumed that these disclosures will be tagged in the financial section of the report. However, if a disclosure which is normally disclosed in the financial section of a report is not present there but is only present in the Directors' Report, then it must be tagged there.
4.9 Fixed value tags
Fixed value tags must be used in combination with an appropriate domain member of the dimension associated to them to unambiguously identify specific contexts.
4.9.1 RULE
Software MUST support the correct application of fixed value tags, ensuring that each use of such a tag is combined with an appropriate domain member from the associated dimension that defines the meaning of the tag.
4.10 Boolean tags
Boolean tags include '[true/false]' suffix at the end of their labels. These tags are designed to indicate whether or not a particular condition applies, representing a specific declaration of circumstance within an iXBRL report.
A number of Boolean tags, including those representing a claim of exemption by an entity, need only be included in an iXBRL report if the 'TRUE' status applies. They MAY be omitted if this status does not apply (i.e. if they were to take a 'FALSE' value). This is to save tagging effort and to reflect the fact that such statements may only appear in accounts when the status applies. The documentation label indicates the tags that may be omitted if 'false' applies. (It is not an error to include such tags, provided they are given the correct value.) Other Boolean tags MUST be included whether they take a true or false value.
4.10.1 RULE
Preparers MUST ensure that Boolean tags representing company declarations are correctly entered with the right value in iXBRL reports since these will be treated as formal declarations by the company. These MUST be consistent with textual statements in the human-readable version of a report.
Software should support preparers in assigning correct values to required Boolean tags.
4.10.2 RULE
Software MUST support efficient entry of Boolean tags.
4.11 Tagging of numeric data
Numeric data in accounts may be presented in a variety of formats, but it must be entered as XBRL values in a consistent way. iXBRL enables underlying XBRL values to be transformed into alternative presentation formats that are suitable for human readers. For example, an underlying XBRL value of 3500 may be presented to the reader as 3,500, 35 hundred or 3.5 thousand.
A number that appears in the human-readable view of an iXBRL report is thus not necessarily identical in format to the underlying XBRL value, but it must have the same meaning.
The underlying value in XBRL must follow rules on XBRL data entry. XBRL requires numbers to be entered in a format 'nXd' where n represents an indeterminate set of figures before the decimal point, X represents a decimal point, if required, and d represents any figures after a decimal point. Examples of valid numbers entered in an iXBRL report include ‘56831244', '8162' and '4.5'. The XBRL decimals attribute determines the number of decimal places to which a particular figure is accurate.
The preparer is free to choose the format of presentation of numbers in the human-readable accounts. Scale factors and transformation rules in iXBRL enable the transformation of an XBRL value into a format aimed at a human reader, so that 3500 may be presented as 3.5 thousand. Software should provide preparers with a simple means of controlling numbers and their presentation without the need for them to understand underlying XBRL rules and terminology.
4.12 Tagging of text
Tags for textual data cover the following purposes:
- Identification of important data, such as the name of the entity concerned;
- Confirmation that certain information is present in a report; and
- Identification of significant textual information that can then be easily located, viewed, compared, collated or stored for further examination. (Analysis of textual content may be performed by human readers or text analysis software.)
Text tags, which are all of 'stringItemType' data type, fall under the following general headings:
- Names;
- Basic descriptions (e.g. Description of material intangible asset);
- Standard statements (e.g. Directors acknowledge responsibilities under the Companies Act);
- Statements of information (e.g. Statement on reasons for any qualification of audit opinion);
- Free-text comment tags.
Text tags are used for specific textual financial information that may be reported in accounts. The text tags cover a full item of textual information rather than detailed parts. Very granular text tags are not used in the taxonomies. This reduces the number of required concepts and simplifies tagging, while continuing to provide all the information likely to be required for the location, analysis, comparison or storage of tagged information. Monetary or numeric concepts which applies to the data concerned are necessary to tag important monetary or numeric data which is nested within a block of text.
The taxonomies do not provide concepts to represent large blocks of text, such as the full Directors' Report. XBRL is intended to represent discrete items of information, so that these may be analysed by software or be easily found, collated and compared. For example, there are concepts to represent individual accounting policies, but there is no concept to represent all policies as a whole.
Labels of basic description text tags mainly begin with the words 'Description of...' or, if covering an accounting policy, end with the suffix '...policy'. Some high-level description tags start with the words 'General description of...'.
Free-text comment tags contain the words 'free-text comment' as in 'Property, plant and equipment free-text comment'. They are intended to cover supplementary textual explanation that may commonly appear in certain notes.
Dimensions may be used with text tags in the same way as numeric tags. For example, the policy on a particular class of PPE may be identified by combining the 'Property, plant and equipment policy' concept with the appropriate dimension for that class.
The scope of text covered by a text tag is governed by the following rule:
4.12.1 RULE
Text tags MUST be applied to the full content of the textual data that they represent. They MUST NOT be applied to just a portion of the data. This is intended to ensure that all relevant data is captured by a tag.
The taxonomies are expected to be used with the iXBRL 1.1 version which allows a single text tag to be applied across different fragments of text. Text that is spread over different pages or is divided before and after a financial table may thus be covered by a single tag. This ability to concatenate related text under a single tag should make tagging easy to apply and more useful to consumers. Concatenation is handled using the ix:continuation element, as introduced in iXBRL 1.1 specification.
4.12.2 RULE
Software MUST support the application of a text string tag across separate sections of text in accordance with the latest version of the iXBRL Specification.
4.13 Tagging of numeric data presented within text
Where appropriate tags exist both for a section of text and for numeric data within the text, then both the text and the numeric data MUST be tagged.
4.13.1 RULE
Significant numeric data presented within text in the financial section of a report MUST be tagged with the appropriate numeric tags for that data. It MUST NOT be hidden within a text tag or within an XBRL footnote.
This rule is intended to prevent numeric data being hidden from analysis software by tagging it as text or placing it within a footnote. The choice between reporting numeric data as a line item or placing it in a footnote may not be important to a human reader, but it is important when data is encoded in XBRL. Note that this rule is not concerned about how data is displayed in a human-readable presentation – but purely about how it is tagged.
4.14 Explicit dimension default members
As explained in section 3.2.1, most explicit dimensions in the taxonomies include default domain members. A limited number of explicit dimensions do not include a default member.
4.14.1 RULE
When using a concept associated with a dimension that lacks a default member, preparers MUST explicitly select and apply a domain member from that dimension to ensure the data point is correctly tagged.
This would not be essential if the concept is also attached to another hypercube containing dimensions with defaults, since that hypercube would then apply, but this condition does not exist in the taxonomies. The concepts attached to dimensions without defaults are not attached to alternative hypercubes. Effectively, the lack of a default member forces a preparer to make a selection from the dimension.
4.15 Use of generic dimension domain members
As explained in section 3.3.7, a number of dimensions contain 'generic domain members' to represent classes of information where the precise members of the class are not known in advance.
The following rules apply to the use of generic domain members.
4.15.1 RULE
When a generic dimension domain member is used in an iXBRL report the associated name or description concept MUST be used in combination with the generic member to provide a human readable identification.
For example, generic domain members such as 'Director 1', 'Director 2' must be used in combination with the appropriate name or description concept, such as 'Name of entity officer'.
4.15.2 RULE
Generic dimension domain members MUST be used consistently within a report. Any disclosure tagged with a particular generic dimension domain member MUST relate uniquely to that single dimension domain member.
For example, if Director 1 has been identified as Joe Bloggs, then the Director 1 dimension domain member must be used consistently throughout a report to apply only to data related to Joe Bloggs. A single generic domain member must not be used to tag different things within a single report.
4.15.3 RULE
Software MUST support the correct use of a name or description tag with any generic dimension domain member which occurs in an XBRL report.
The choice of mechanisms for achieving this is up to software developers. They may include warning messages and prompts to users, ensuring that whenever a generic domain member is used in a report, it is accompanied by its corresponding name or description tag.
4.16 Use of ‘non-standard' and 'further item' dimension domain members
As explained in section 3.3.8, a number of dimensions contain 'non-standard' or 'further item' dimension domain members to handle breakdowns of classes of information which cannot be fully defined in advance.
The following rules apply to the use of these dimension domain members:
4.16.1 RULE
'Non-standard' and 'further item' domain members of a dimension MUST only be used:
- If no other suitable domain member is available for the class of information concerned.
- For classes of information that are a direct component of the relevant total. They MUST NOT be used to tag classes that are breakdowns of an intermediate sub-total and are thus not direct components of the total concerned.
In other respects, 'non-standard' and 'further item' domain members MUST be used in the same way as other dimension domain members.
These rules are intended to ensure consistent use of the non-standard and further item domain members and to avoid double counting if summation is checked.
The rules may mean that certain breakdowns of intermediate classes are not tagged. However, top-level classes should be tagged comprehensively, and their summation may be tested.
For example, the PPE classes dimension includes tags for 'Vehicles' and component classes such as 'Aircraft'. It does not include 'Large aircraft' and 'Small aircraft'. If a report includes the "Large aircraft' and 'Small aircraft' classes, these must be tagged with the non-standard PPE dimension domain members if they are shown in the report as direct components of the PPE classes total. However, if they are shown as components of an intermediate sub-total, such as ‘Vehicles' or 'aircraft', then they must not be tagged. This will avoid double counting.
If a report contains a greater number of untypical classes than can be covered by non-standard tags, then some classes will have to be left untagged.
4.16.2 RULE
If a report contains a greater number of untypical classes than can be covered by available non-standard tags, then the most significant of the untypical classes, either by monetary value or other appropriate measure of materiality, SHOULD be tagged in preference to less important classes.
4.17 Use of further item concepts and analysis typed dimension
As explained in section 3.3.9, further item concepts and analysis typed dimension are intended to enable the tagging of disclosures for which no specific concept exists.
The following rules apply to the use of further item concepts and the analysis typed dimension:
4.17.1 RULE
A further item concept with an analysis typed dimension MUST only be used
- when no other suitable concept or combination of concept and dimension is available for the disclosure concerned.
- within the section for which it is intended.
In other respects, further item concepts MUST be used in the same way as other concepts. In particular, ordinary dimensions MUST be used appropriately with further item concepts, when the meaning of the data requires this.
These rules are intended to ensure that further item concepts can be correctly interpreted by consumers and do not lead to double counting if summation is checked.
If a set of data is identified as for continuing operations, then all entries, including those tagged with further item concepts, must be tagged with the continuing operations dimension. In other words, the use of further item concepts does not imply any loosening of rules on applying the closest available tagging.
4.17.2 RULE
Further item concepts MUST only be used for disclosures that are a direct component of the total to which the further item refers. Entries that are breakdowns of an intermediate sub-total and are thus not direct components of the total MUST NOT be tagged with a further item that points to the total.
For example, a concept for 'Amounts recoverable on contracts' exists under debtors in FRS-102 entry point. However, a report may include debtor entries for 'Amounts recoverable on construction contracts' and 'Amounts recoverable on consultancy contracts'. These have no directly equivalent concepts. If they are shown in the report as direct components of debtors, i.e. without a parent total for amounts recoverable on contracts, then they must each be tagged with the further item concept 'Further item of debtors [component of total debtors]'. This will help ensure all direct components of debtors are tagged and the basic summation of debtors items can be checked.
However, if the two items are simply shown in a report as a breakdown of amounts recoverable on contracts, with the latter value present in the report, then the two items must not be tagged. They are already represented in the value of debtors through their parent total, which will be tagged.
| Total debtors | |
|---|---|
| Trade debtors | |
| Amounts recoverable on contracts | |
| Amounts recoverable on construction contracts | Must not be tagged |
| Amounts recoverable on consultancy contracts | Must not be tagged |
| Advances paid to suppliers |
| Total debtors | |
|---|---|
| Trade debtors | |
| Amounts recoverable on construction contracts | Must be tagged with further item |
| Amounts recoverable on consultancy contracts | Must be tagged with further item |
| Advances paid to suppliers |
It is understood that the use of further items will not guarantee that a particular section will always sum correctly according to a simple formula. The variability of items that may be included in some financial aggregations may mean the summation implied in a taxonomy will not match that used in some specific accounts. For example, companies may apply varying definitions to what is contained within sections such as operating income, non-operating income and revenue. However, the use of further item concepts will: (a) enable more complete tagging, (b) allow summation to be confirmed in many cases, and (c) encourage checks on the correctness of tagging where summation fails.
4.17.3 RULE
The same set of information in a different time period MUST also carry the same integer value of the analysis typed dimension, enabling easy comparison across periods.
Different sets of information MUST be distinguished by a different integer value of the analysis typed dimension.
Duplicate further item facts in the report MUST carry the same integer value of the analysis typed dimension.
For example, when using the further item of operating income, preparers must assign the same integer value of the analysis typed dimension, both in the current and previous periods. A different further item of operating income would be identified by a different integer value of the analysis typed dimension.
Software should identify further item concepts to users and support users in applying these concepts correctly.
4.17.4 RULE
Software MUST identify further item concepts clearly in displays and provide supporting information to aid their correct use. Software MUST handle the integer value of the analysis dimension domain so that identical items are assigned the same integer, but different items are assigned a different integer.
For example, software might automatically cycle the integer value of the analysis typed domain if a preparer makes repeated use of a further item concept for different disclosures. However, software should make clear to users the integer value and the application of the further item concept, so that the same entry across time periods or duplicate entries will carry the same integer.
4.17.5 RULE
Concepts labelled as representing 'other' amounts SHOULD be used to tag disclosures identified as 'other' or 'residual' in a financial report. If they exist in a section that also contains a further item concept, they MUST NOT be used to tag entries unless these are specifically identified as 'other' or as a residual amount. If they are in a section that does not include a further item concept, they MAY be used to tag a specific entry, if no 'other' entry exists in that section of the report. These cases will be rare since most sections that contain an 'other' concept also include a further item concept.
A number of concepts represent a residual amount from a list of items. An example is ‘Other creditors'. These are intended for tagging disclosures that are described as 'other' in a financial report. The purpose of this rule is to avoid confusion between the role of further item concepts and concepts for 'other' amounts.
4.18 Use of grouping tags
As explained in section 3.3.10, a 'grouping' is used to contain concepts that describe related aspects of a particular piece of information and are expected to be used in combination.
The following rules apply to the use of grouping tags:
4.18.1 RULE
Concepts in a grouping that are applied to a particular set of information MUST all be linked to the same integer value of the grouping typed dimension.
Duplicate grouping facts in the report MUST carry the same integer value of the grouping typed dimension.
The same set of information in a different time period MUST also carry the same integer value of the grouping typed dimension, enabling easy comparison across periods.
Different sets of information MUST be distinguished by a different integer value of the grouping typed dimension.
In other respects, grouping concepts may be attached to any range of dimensions in addition to the grouping typed dimension.
For example, when using the 'material bank loan' grouping, which ties together the description of a loan and its amount, preparers must assign the same integer value of the grouping typed dimension to the description and amount of a particular loan, both in the current and previous periods. A different loan would be identified by a different integer value of the grouping typed dimension.
Normal tagging rules apply to all facts tagged with grouping concepts. Ordinary dimensions must be applied to them, as required.
Software should identify grouping items clearly to users and support users in applying grouping tags correctly.
4.18.2 RULE
Software MUST identify grouping parents and the concepts within them clearly in displays and provide supporting information to aid their correct use. Software MUST handle the integer value of the grouping typed dimension domain effectively, so that:
- the same integer value is assigned to items in the same occurrence of the grouping; and
- different integer values are assigned to different occurrences.
Clear identification of grouping items should help users in understanding and applying them correctly. Software should help users apply the same integer value to all items in the same occurrence of a grouping, including an occurrence reported across different period types.
In tracing links of concepts to hypercubes, developers should note that the same hypercube can occur in different ELRs, with different dimensional children in each case.
4.19 Entity information
The entity aspect identifies the specific organisation to which the fact relates to ensure there is no confusion between similar company names. It consists of two components:
- a URL of the identification scheme that defines the entity; and
- the unique code used for the entity within that scheme.
For example, a UK entity is typically identified either by its Companies House registration number via the identifier House scheme (http://www.companieshouse.gov.uk/) or by its Unique Taxpayer Reference (UTR) via the identifier scheme (http://www.hmrc.gov.uk/).
Similarly, an Irish entity is typically identified either by its Corporation Tax tax head number via the identifier scheme (http://www.revenue.ie/) or by its Company Registration Office (CRO) number via the identifier scheme (http://www.cro.ie/).
HMRC, Companies House, and the Irish Revenue establish specific mandates regarding the use of permissible entity identifiers. These regulatory authorities publish their respective requirements within their official documentation.
4.19.1 RULE
All entities MUST use an entity identifier scheme permissible by its respective regulatory authority, along with the unique code used for the entity within that scheme.
4.19.2 RULE
Software MUST support the correct setting of entity contexts to identify the entity to which iXBRL data applies.
4.20 Period information
The dates that apply to a fact are covered by the period aspect. This is quoted in terms of a calendar date (yyyy-mm-dd) and may apply either to an instant (yyyy-mm-dd) or to a duration (from yyyy-mm-dd to yyyy-mm-dd). Disclosures that apply to different periods are not represented by different concepts. They are represented by the period aspect applied to a fact. For example, the same concept is used for operating profit for Year 2 as for Year
- Similarly, values at the beginning and end of periods are also distinguished by the period aspect, not by the concept.
4.20.1 RULE
Disclosures SHOULD be tagged with concepts of the correct period type.
This rule aids accurate tagging as well as ensuring the correct processing of data in iXBRL reports. For example, applying a concept with a 'Duration' period type to an 'Instant' fact is a common tagging error; such a discrepancy suggests that the chosen taxonomy element does not correctly align with the nature of the disclosure.
There is a qualification to this rule where a dimension is applied to an 'instant' item in order to express a movement. This occurs with financial instrument tags that are attached to dimensions expressing various movements, such as movements in fair value. In these special and limited cases, the application of the dimension effectively transforms the nature of the tagging to express a change over time, although the line item concerned is a of an instant type. For this reason, the rule is expressed as a 'SHOULD' rather than a 'MUST'. In other situations, however, the rule always applies.
4.20.2 RULE
The assignment of a period aspect to a fact in an iXBRL report MUST be consistent with both the period covered by the report and the data concerned. Period contexts will thus align with reporting periods. For example, ‘Operating profit (loss)' over a financial year ending on 31 March Year2 will have a period aspect reflecting the duration from 1 April Year1 to 31 March Year
- 'Net assets (liabilities)' at the end of the period will have a period aspect of the instant 31 March Year2.
4.20.3 RULE
The period aspect of specific events MUST have a value reflecting the period covered by the report – they do NOT take values matching the specific date they contain.
For example, the period aspect of a revaluation of property, plant and equipment, which is of an instant type, must have a value reflecting the end of the reporting period (the balance sheet date) – not the date of the valuation. Similarly, the date of signing of the balance sheet should also have a period aspect value reflecting the balance sheet date – not the date of signing, which may be somewhat after the period covered by the report. This approach avoids preparers having to create a multiplicity of contexts to reflect different events.
4.20.4 RULE
Software MUST support the correct setting of period contexts. The start period of a duration is defined by convention as midnight at the start of a day. The end period of a duration and the instant date are defined by convention as midnight at the end of a day. An important consequence of this is that an instant date for the beginning of a period is actually midnight on the previous day. In other words, the instant date for the period beginning 1 Jan Year2 is actually 31 Dec Year
- (An instant date of 1 Jan Year2 means midnight on that day, 24 hours into the period.) Note that this reasoning applies to instant contexts, not durations.
This has important consequences for the way context dates are assigned to movement analyses and similar data. A movement analysis covering two contiguous periods requires five context dates, not seven. An example is shown below.
- Value at end of previous year, 31 Dec Year1 (instant context Year1-12-31)
- Value at start of year, 1 Jan Year2 (also instant context Year1-12-31)
- Value at end of year, 31 Dec Year2 (instant context Year2-12-31)
- Change during the year from 1 Jan Year2 to 31 Dec Year2 (duration context Year2-01-01 to Year2-12-31)
Note that the contexts for lines 1 and 2 are identical. Clearly, the values and contexts for data at the end of one period and the beginning of a consecutive period must be identical.
This may not be intuitively obvious to preparers looking at dates in a human-readable version of accounts. Software must help preparers to assign dates correctly and easily. Ideally, it should hide underlying XBRL reasoning on dates from users.
Clearly, restatements may alter a value at the start of a period, but that is handled through a separate mechanism from dates. Restatements are distinguished through the 'Restatements' dimension.
4.21 Unit information
For any numeric fact (like a currency amount or a number of employees), a unit MUST be provided. This identifies whether the number "5,000" represents £5,000 (GBP), €5,000 (EUR), or 5,000 Shares. For non-numeric facts (like a piece of text or a "Yes/No" answer), a unit is not required.
4.22 Currencies
Concepts with data types as 'perShareItemType' and 'monetaryItemType' will always represent values measured in a currency. The currency is determined by the currency defined in the unit reference (unitRef) attached to each value. Software should give preparers easy ways of controlling the currency of monetary values.
4.22.1 RULE
Software MUST support the correct currency designation to monetary and other items that are measured in a currency.
Software may aid users by enabling them to set the default currency for a report.
Note that the 'Currencies' dimensions defined in the accounts taxonomies are NOT used for assigning currencies to monetary values. One version of the currencies dimension is used for identifying the currencies used in the business report. It is attached to the fixed-value tag ‘Principal currency used in business report'. Another version of the currencies dimension is used to identify the currencies in which particular financial instruments are denominated.
4.23 Scale and Accuracy of values
The scale attribute, defined in the iXBRL specification, determines the scale at which numbers are presented in reports.
The XBRL specification allows two alternative methods of reporting accuracy: decimals and precision. The use of decimals is mandated for XBRL reporting in the UK and Ireland. The decimals attribute, which determines the number of decimal places to which a particular figure is accurate, is vital for determining the true, underlying value of numbers in XBRL. For example, the numbers 12.56 and 12.00 with a decimals attribute of 0 have an identical value of
- The zero decimals attribute means that all numbers after the decimal point are insignificant or unreliable and should be ignored. Similarly, 12.349 and 12.341 with a decimal attribute of 2 have the same value, but with a decimals attribute of 3, they do not.
4.23.1 RULE
The decimals attribute MUST be used in iXBRL reports to indicate the accuracy of numeric values. The precision attribute MUST NOT be used.
4.23.2 RULE
Software MUST support the correct use of the scale and decimals attributes in setting the presentation and accuracy of numeric information in iXBRL reports. The precision attribute MUST NOT be used.
Software should guide users as far as is practical in correct application of these attributes.
4.24 Positive and negative values
The correct positive or negative sign MUST be applied to fact values in an iXBRL report. This sign is determined by rules defined in the taxonomy. It is NOT necessarily the same as the sign that is used in the human-readable view of a report. The latter is controlled by the preparer and will depend on the particular conventions used in a report. Signs are transformed between the underlying fact value and the human-readable presentation using features of iXBRL.
4.24.1 RULE
Preparers of iXBRL reports MUST follow these sign rules:
- Data MUST always be entered as positive UNLESS rule (b) below requires otherwise.
- Where data may be positive or negative, the label will indicate the correct sign of the item. Labels will generally use brackets around terms to show what data should be entered as negative. If no brackets are present, data MUST be entered as positive UNLESS the value is the OPPOSITE of that indicated in a tag label.
Such reversals of sign MUST ONLY be used with concepts which may genuinely represent positive or negative values. They MUST NOT be used to transform the meanings of concepts – for example transforming an assets tag into a liabilities tag and vice versa. Different concepts MUST be represented by different tags.
Examples of sign indicators in labels are:
- Operating profit (loss)
- Net current assets (liabilities)
- Net cash inflow (outflow) from disposal
If a company reports an operating profit, it will thus enter the value of the profit as positive. On the other hand, if it reports a loss, it will enter the value of the loss as negative.
An example of a tag that does not include a bracketed term, but may in rare cases require a value to be entered as negative is 'Cost of sales'. In such cases, a large credit may mean that the cost of sales effectively represents a net credit.
The taxonomies also allocate debit/credit balance type attribute to monetary concepts. This includes cash flow and similar items, using the convention that 'credit' represents an outflow of cash while 'debit' represents an inflow. These are intended to support calculations in software. They may help guide users on the correct sign, but they do not apply to all numeric data, and the wording of labels always takes precedence in determining the sign.
The use of balance types with cash flow items does not tie in with standard accounting practice and the taxonomies include additional information to enable software to convert the credit / debit attributes to outflow / inflow signals.
Custom arcroles in the definition linkbase separately identify cash inflow and outflow tags:
- All cash inflow tags are linked to an 'x-Inflows [heading]' parent tag by an 'inflow' arcrole. (These relationships are defined in the ELR '9992 - Inflows'.)
- All cash outflow tags are linked to an 'x-Outflows [heading]' parent tag by an 'outflow' arcrole. (These relationships are defined in the ELR '9993 - Outflows'.)
4.24.2 RULE
Software MAY supplement or replace balance attribute information on cash flow tags by identifying them as 'inflow' or 'outflow' items. All cash inflow items are the target of an 'inflow' arc in the definition linkbase and all cash outflow items are the target of an 'outflow' arc in the definition linkbase.
All cash flow monetary items carrying a balance attribute are a target of either an inflow or outflow arc.
4.24.3 RULE
Software MUST support the correct application of positive or negative signs to numeric data.
While sign allocation is straightforward for most data, it can be confusing in certain cases. Correct allocation is clearly vital to provision of accurate XBRL information. Software developers should implement all reasonable mechanisms to support the accurate application of signs.
4.25 Use of 'free-text comment' tags
4.25.1 RULE
Free-text comment tags MUST only be used to cover supplementary comments in the specific area to which they apply. They MUST NOT substitute for specific tags where the latter would be appropriate.
For example, free-text comment tags should be used to tag a general explanation that might appear at the bottom of a note to the accounts, for which no other suitable tag exists.
4.26 Nesting of Tags
Disclosures may be 'nested' within data tagged with a text tag. Monetary, numeric and other types of tags may all be applied within a block of text that has been tagged with a text tag.
Numeric tags may also be nested together under strict conditions. The numeric tags must be applied directly around one another, without intervening text. Effectively, this allows the same piece of data to be tagged with a series of numeric tags.
This will only be valid if the data is in the correct format for the different numeric tags concerned – for example in a number format if a 'decimal item type' tag is used.
This nesting is useful if a single number or monetary item represents more than one piece of information, for example if a report uses a single figure for both current and previous periods or for the percentage ownership of a number of different subsidiaries. Multiple numeric tags identifying the different meanings may be applied to the single disclosure.
4.26.1 RULE
Software SHOULD support the nesting of numeric tags in iXBRL. Software MUST support the nesting of tags within text tags.
4.27 Tagging of footnotes
Taxonomies do not contain elements to represent footnotes. These are handled through the XBRL footnote mechanism which allows preparers freely to attach footnotes to any fact. If significant numeric information is contained within a footnote, this data must be tagged in the ordinary way.
The availability and use of the XBRL footnote mechanism is dependent on the software used for preparing iXBRL reports. If relevant footnotes are not attached to facts using the XBRL footnote mechanism, anyone analysing raw XBRL data will not be aware that an explanatory footnote is available.
Free-text comment tags are intended to reflect general subsidiary comment on a statement or note, not footnotes on particular disclosures. In some cases they may be suitable for tagging footnotes, but they do not provide a general solution.
4.28 Dates
Concepts with the data type as 'dateItemType' require XBRL values in the format yyyy-mm-dd. Conversion into other formats for human-readable presentation can be achieved through iXBRL transformation rules.
Dates that are not reported at this level of precision are represented in the taxonomy by text / string type tags. This enables the entry of date ranges or dates by month or year. Software should enable preparers easily to enter dates in the correct format.
4.28.1 RULE
Software MUST support entry of dates in the correct format.
4.29 Percentages
Percentages are represented by concepts with the data type as 'num:percentItemType'. XBRL requires that percentages MUST be entered as XBRL values using decimal notation, so that 60% is represented in XBRL as 0.6. iXBRL enables this to be converted into a normal presentation in human-readable accounts. Software should enable preparers to enter percentages in a simple and efficient manner, without the need for them having to be aware of XBRL rules on the formatting of percentages.
4.29.1 RULE
Software MUST support the entry of percentages in the correct format.
4.30 Unreported data
4.30.1 RULE
Disclosure that is listed in a financial statement but is not reported, such as data represented by a dash or a blank in a table, SHOULD NOT be tagged.
Disclosures that are represented by dashes or similar indicators of unavailability should be treated as not reported. They should therefore be left untagged. (Tagging such disclosure requires it to be assigned a value, such as zero. This will generally not be the meaning a preparer wishes to convey.)
4.31 Use of XBRL nil values
In general, if no value is being reported for an item, it is not expected to be tagged, as stated in section 4.19. If preparers wish to report an exact value of zero, they should tag the item with the numeric value
- However, if preparers wish to tag a line item in a report for which no value is reported (as opposed to a value of zero), they may include the appropriate tag with an XBRL ‘nil value'. The latter means 'null' or 'not reported' – it does not mean zero.
If preparers wish to explain why a particular item is not reported, they may do so by assigning it a nil value and attaching a footnote explaining the reason using the XBRL footnote mechanism. Without an explanation, the meaning of the nil value will not be clear. It may cover a host of meanings, including data not available, not known or confidential. The inclusion of tags with nil values and no explanation may prompt queries from data collectors and consumers.
4.32 Tagging of comparative data
4.32.1 RULE
Comparative data for preceding periods in financial reports MUST be tagged, just as data for the most recent period is tagged. This rule includes previous period data for which no current data is published.
4.33 Compulsory tags
HMRC, Companies House, FCA, and Irish Revenue establish specific mandates regarding compulsory tags and other aspects of filing. These regulatory authorities publish their respective requirements within their own official documentation.
4.34 Distinction of company and group data
The dimension domain members 'Consolidated' and 'Company [default]' exist to distinguish group and company data. Their use will normally be straightforward, with company being the default.
In some cases, however, an organisation may present some data in its accounts as applying to both group and company. For example, such combined accounts may show separate balance sheets for the group and the company, but a single table for property, plant and equipment (PPE), with the same PPE values applying to both group and company. The general rule for handling such cases in iXBRL is:
4.34.1 RULE
When group and company data in a financial report is being tagged, a disclosure which represents a value for both the company and the group MUST be tagged twice: once using the appropriate 'Consolidated' domain member to identify the data as relating to the group and once with a 'company [default]' domain member, indicating that it relates to the company. Other tags attached to the disclosure will be identical.
This double tagging of information May be achieved by nesting of the tags applied to the data. It is not necessary physically to duplicate the data in the iXBRL report.
4.35 Revised data
The 'Original and revised data' dimension with two domain members 'Superseded' and 'Currently stated [default]' exists to distinguish original and revised (amended) data. Revision can take two forms: by amendment and by supplementary note.
Under normal circumstances, with no specific amendments to report, the default member applies (i.e. everything is regarded as “revised” with respect to the previous version, if any, of the report), but where revisions (amendments) are being tagged (i.e. revision by amendment) the specific disclosures that represent the original values should be tagged with the 'Superseded' domain member of the dimension and the disclosures that represent the revised data should be tagged with the default. If, however, the revision is by supplementary note then the 'Superseded' domain member should not be used.
'Currently stated' is the default so that validation and/or data analysis rules can be applied to a mixture of original and revised data without having to make special provision for any dimension membership difference. The presence of corresponding disclosures tagged with the 'Superseded' member is intended to act as an indication that these specific disclosures have been revised/amended.
The distinction between the two forms of revision is defined by the tags used in the Revised accounts statements section of 003 - Report Information.
4.36 Completeness, accuracy and summation
The taxonomies are intended to support the complete tagging of the main financial data and schedules in financial statements. The taxonomies help to enable this by providing:
- Further item concepts with analysis typed dimension
- Grouping concepts with grouping typed dimension
- 'Non-standard' and 'further item' dimensions
4.36.1 RULE
Software MUST support users in achieving as complete tagging as practical of the main financial data and schedules in financial reports and in helping to test the completeness and accuracy of tagging.
The means of achieving this is up to developers. However, testing the summation of the components of some key facts against the reported total provides one means of checking the completeness and accuracy of tagged data.
The UK and Irish digital reporting taxonomies Guide published on the FRC website includes a zip file outlining consistency check which may be used to test summation and other aspects of tagged data.
The use of analysis typed dimensions, and other techniques will not guarantee that particular sections of tagged data will always sum correctly. However, many sections may be expected to do so in the general case. Consistency checks of various types should allow the completeness and accuracy of tagging to be tested and help preparers of tagged accounts to identify errors or weaknesses in tagged information.
4.37 Summation and checking of tagging
The design of the taxonomies, and particularly the introduction of further item concepts and analysis typed dimensions, implies relevant sections of accounts may be tagged comprehensively and that the tagged data within them may be successfully summed. The summing of tagged data and checking against tagged totals provides a means of testing the accuracy of tagging (and potentially a check on the correctness of totals in the accounts).
The FRC has published a set of consistency checks covering expected summations and other relations involving tagged data which can be found on the FRC website.
Such consistency checks are purely intended as a helpful support to improve the quality of tagging. They are intended to provide information to taxonomy users. They are not intended to be an infallible guide on which acceptance or rejection of accounts might be based. The variability in the content of accounts across companies and industry sectors means that it is difficult to set rules and formulae which will all hold true in all circumstances for all entities.
The taxonomies do not include XBRL calculation linkbases.
4.38 Taxonomy Extensions
Preparers of iXBRL reports are not expected to create custom taxonomy extensions of the UK and Irish Digital reporting taxonomies to define elements for entity-specific data not covered by the taxonomies. The taxonomies are intended to cover all current tagging requirements for filing of accounts information to HMRC, Companies House, and Irish Revenue. However, a notable exception applies to UKSEF filings, where publicly listed entities must create and anchor entity-specific extensions of the ESEF taxonomy for default target document while avoiding extension of the FRC taxonomy for UKFRS target document.
If any entity does create a taxonomy extension of the UK and Irish Digital reporting taxonomies, it must do so according to the strict rules set out below. The extension will otherwise:
- undermine the meaning of tagging based on the original taxonomy; and
- provide inconsistent or unclear tags which cannot be usefully analysed or compared.
4.38.1 RULE
Organisation-specific extensions taxonomies:
- MUST NOT be created UNLESS these are required to represent data which is:
- material to the business report concerned; AND
- not covered in the published taxonomies.
- MUST NOT create tags which broadly duplicate the meaning of tags in the taxonomies.
- MUST NOT change the definition of elements in the taxonomies, for example by removing dimensional links or accounting references or altering basic attributes of tags.
- MUST follow the design and conventions adopted in the taxonomies or described in FRC documents. This is to ensure any extension operates in a consistent way and produces tagged data which can be properly understood.
- MUST NOT be created for purely presentational purposes, such as amendment of taxonomy labels. Presentational requirements MUST be handled using iXBRL.
Appendices
A: Glossary
| Term | Definition interestd data from software. |
|---|---|
| Arc | Used to link items in the linkbase files which define relationships in a taxonomy. Arcroles define the nature of each link. See Appendix E for the arcroles used in the taxonomies. |
| Charities SORP | Statements of Recommended Practice (SORPs) are sector-driven recommendations on financial reporting, auditing practices and actuarial practices for specialised industries, sectors or areas of work, or which supplement FRC standards and other legal and regulatory requirements in the light of special factors prevailing or transactions undertaken in that particular industry, sector or area of work that are not addressed in FRC standards. The Charities SORP is applicable to charities preparing their accounts in accordance with FRS 102, is issued by the Charity Commission for England and Wales, the Charity Commission for Northern Ireland and the Office of the Scottish Charity Regulator in their role as the joint SORP-making body, recognised by the Financial Reporting Council. The Charities SORP provides recommendations and requirements setting out how to prepare 'true and fair' accounts in accordance with FRS 102. A charity preparing its accounts in accordance with Charities SORP must also comply with the SORP's trustees' annual report requirements in order to claim compliance with the SORP. |
| Context | The XBRL context applied to a fact represents the time period, the entity to which the data applies and dimensional information. |
| Data types | Taxonomy tags are assigned a 'data type' to identify their meaning and role and to assist in processing XBRL data. |
| Dimensions and domain members | Taxonomy dimensions represent the different forms in which financial data may be reported. A dimension domain member is used to represent each individual form of reporting. |
| Extension taxonomy | An extension taxonomy modifies another taxonomy by adding tags, providing alternative presentation views or other changes. The filing of iXBRL reports in the UK is not expected to require entity-specific extension taxonomies. |
| Financial Reporting Council | The Financial Reporting Council (FRC) is the UK's independent regulator which sets standards for corporate reporting, audit and actuarial practice and which monitors and enforces accounting and auditing standards. |
| Fixed value tags | Fixed value tags are identified in the taxonomy by the custom data type 'types:fixedItemType'. They have a predefined fixed value of 'nil'. They have their effect simply by being included in an iXBRL report in combination with an appropriate dimension. An example is 'Country of formation or incorporation'. This is attached to the 'Countries' dimension. The country of incorporation is identified by selecting the appropriate domain member from the country dimension. |
| FRS 101, FRS 102, FRS 103, and FRS 105 | Accounting standards applicable in the UK and Republic of Ireland issued by the Financial Reporting Council. |
| Generic dimension domain members | Generic dimension domain members represent classes of information where the precise name of each member of the class is not known in advance. Examples include individual directors, individual subsidiaries, operating segments, share schemes, pension scheme and the like. A generic dimension domain member consists of the name of the class followed by a number to indicate the individual tag. Generic dimensions are tied to name or description concepts which identify the use of each generic tag. |
| IFRS Accounting Standards | IFRS® Accounting Standards and interpretations issued by the International Accounting Standards Board (IASB). They comprise: (a) International Financial Reporting Standards; (b) IAS® Standards; (c) IFRIC® Interpretations developed by the IFRS Interpretations Committee; and (d) SIC® Interpretations developed by the former Standing Interpretations Committee. |
| Inline XBRL or iXBRL | The Inline XBRL, also known as iXBRL, provides a human-readable version of the report based on XHTML, with XBRL tags normally hidden from view in the underlying file. |
| Labels | Labels are the human-readable description on XBRL tags, which provide their main definition. As far as possible, they uniquely identify the tag concerned. |
| Manual tagging | The process of manually applying XBRL tags to items in financial statements with the aid of software. This involves the mapping of tags in a XBRL taxonomy to items contained in the financial statements. |
| Period type and context | All concepts have a period type which identifies whether they are measured at an 'instant' or over a 'duration'. The period context represents the precise dates over which they are measured. |
| SECR | Streamlined Energy and Carbon Reporting |
| TCFD | Task Force on Climate-related Financial Disclosures |
| Tag | An XBRL tag is the machine-readable identifier attached to an item of business data. |
| Typed dimension | A special type of dimension which does not contain a set of specific, predefined dimension domain members, but is defined by some general property. The typed dimensions used in the taxonomies are defined as containing domain members represented by positive integers. They thus effectively provide anonymous tags which enable the line items tags attached to them to be reused any number of times. They are used for further item concepts and grouping concepts. |
| Taxonomy | Taxonomies are the dictionaries of the XBRL language, containing the machine-readable tags used to identify specific financial and business disclosures. |
| UKSEF Approach | UK Single Electronic Format Approach The UKSEF approach uses a standard feature of iXBRL called Multiple XBRL Target Documents. |
B: Data types
The following data types are used in the taxonomies:
| # | Common name | Purpose | XBRL name |
|---|---|---|---|
| 1 | Monetary | To represent monetary values | monetaryItemType |
| 2 | String item / text item | To represent ordinary textual information | stringItemType |
| 3 | Decimal | To represent ordinary numbers | decimalItemType |
| 4 | Shares | To represent numbers of shares, options and related instruments | sharesItemType |
| 5 | Per share | To represent values per share | num:perShareItemType |
| 6 | Percent | To represent percentage values | num:percentItemType |
| 7 | Date | To represent specific dates in a yyyy-mm-dd format | dateItemType |
| 8 | Boolean | To represent true / false statements | booleanItemType |
| 9 | URI | To represent URIs | anyURIItemType |
| 10 | Domain member | To represent usable values of a dimension | nonnum:domainItemType |
| 11 | Pure | To represent pure values | pureItemType |
| 12 | Energy | To represent energy values | num:energyItemType |
| 13 | Greenhouse gas emissions item type | To measure Global Warming Potential | dtr2022:ghgEmissionsItemType |
| 14 | Nonnegative decimal | To represent nonnegative ordinary numbers | types:nonNegativeDecimalItemType |
| 15 | Fixed item | Items taking predefined values | types:fixedItemType |
| 16 | Grouping Item | Parents of groupings | types:groupingItemType |
| 17 | Guidance item | Items providing information or guidance | types:guidanceItemType |
| 18 | Heading item | Headings of sections | types:headingItemType |
| 19 | Cross-reference item | Items pointing to other related information | types:xrefItemType |
Data types 1-13 are defined by XBRL International. Data types 14-19 are custom data types defined in the UK and Irish digital reporting taxonomies.
C: Fixed value tags
The following are the tags in the taxonomies of 'fixedItemType'.
| # | Label | Key dimension |
|---|---|---|
| 1 | Country of formation or incorporation | Countries and regions |
| 2 | Country in which parent of largest group is incorporated | Countries and regions |
| 3 | Country in which parent of smallest group is incorporated | Countries and regions |
| 4 | Country of incorporation or residence of associate | Countries and regions |
| 5 | Country of incorporation or residence of joint venture | Countries and regions |
| 6 | Country of incorporation or residence of subsidiary | Countries and regions |
| 7 | Director signing financial statements | Entity officers |
| 8 | Director signing Directors' Report | Entity officers |
| 9 | Principal currency used in business report | Currencies |
| 10 | Other currency used in business report | Currencies |
| 11 | Entity trading status | Entity trading status |
| 12 | Report period | Report period |
| 13 | Report principal language | Languages |
| 14 | Scope of accounts | Scope of accounts |
| 15 | Accounting standards applied | Accounting standards |
| 16 | Accounts status, audited or unaudited | Accounts status |
| 17 | Accounts type | Accounts type |
| 18 | Applicable legislation | Applicable legislation |
| 19 | Entity is under special legal status | Entity special legal status |
| 20 | Legal form of entity | Legal form of entity |
| 21 | Main industry sector | Main industry sector |
| 22 | SORPs applied | SORPs |
The key dimension column shows the dimension which principally identifies the value of each fixed item type tag. The dimensions in rows 1-14 have defaults; those in rows 15-22 do not. The default values are not necessarily the expected value for the fixed item type tags. The dimensions concerned have broad uses and are attached to a range of concepts. Users MUST select the correct domain member from the dimension for each occurrence of a fixed item type tag.
Future versions to the taxonomies for industry sectors may introduce new fixed value tags.
D: Generic dimensions
The table below shows generic dimensions and their associated name or description tag.
| Dimension | Domain members | Taxonomies | Related name or description concept |
|---|---|---|---|
| Continuing and discontinued operations | Specific discontinued operation 1 to 8 | All | Description of discontinued operation or non-current assets or disposal group held for sale |
| Specific non-current assets / disposal group held for sale 1 to 8 | All | Description of discontinued operation or non-current assets or disposal group held for sale | |
| Chairman | All | Name of entity officer | |
| Chief executive | All | Name of entity officer | |
| Chairman and chief executive | All | Name of entity officer | |
| Senior partner, limited liability partnership | All | Name of entity officer | |
| Entity officers | Company secretary 1 to 2 | All | Name of entity officer |
| Company secretary and director 1 to 2 | All | Name of entity officer | |
| Director 1 to 40 | All | Name of entity officer | |
| Partner, LLP, 1 to 20 | All | Name of entity officer | |
| Trustee 1 to 20 | Char | Name of entity officer | |
| Corporate trustee 1 to 3 | Char | Name of entity officer | |
| Director 1 of corporate trustee to 3 | Char | Name of entity officer | |
| Custodian trustee 1 to 3 | Char | Name of entity officer | |
| Operating segments | Reportable operating segment 1 to 20 | All | Name of individual segment |
| Products and services | Product and service 1 to 12 | All | Name of individual segment |
| Major customers | Major customer 1 to 12 | All | Name of individual segment |
| Business combinations | Specific business combination 1 to 10 | All | Name of acquired entity |
| Biological asset classes | Consumable biological asset class 1 to 5 | All | Name or description of biological asset class |
| Bearer biological asset class 1 to 5 | All | Name or description of biological asset class | |
| Subsidiaries | Subsidiary 1 to 200 | All | Name of subsidiary |
| Associates | Associate 1 to 50 | All | Name of associate |
| Joint ventures | Joint venture 1 to 50 | All | Name of joint venture |
| Unconsolidated structured entities | Unconsolidated structured entity 1 to 5 | All | Name of unconsolidated structured entity |
| Intermediate parent 1 to 5 | All | Name or description of related party [if not defined by another tag] | |
| Entity with joint control or significant influence 1 to 5 | All | Name or description of related party [if not defined by another tag] | |
| Another group member 1 to 8 | All | Name or description of related party [if not defined by another tag] | |
| Related parties | Trustee / trustees 1 to 5 | Char | Name or description of related party [if not defined by another tag] |
| Close family member of trustee / trustees 1 to 5 | Char | Name or description of related party [if not defined by another tag] | |
| Entity controlled by trustees 1 to 5 | Char | Name or description of related party [if not defined by another tag] | |
| Key management individual / group 1 to 5 | All | Name or description of related party [if not defined by another tag] | |
| Close family member 1 to 5 | All | Name or description of related party [if not defined by another tag] | |
| Entity controlled by key management personnel 1 to 5 | All | Name or description of related party [if not defined by another tag] | |
| Other related party relationship type 1 to 2 | All | Name or description of related party [if not defined by another tag] | |
| Entity share classes | Ordinary share class 1 to 5 | All | Description of share type |
| Preference share class 1 to 5 | All | Description of share type | |
| Deferred share class 1 to 5 | All | Description of share type | |
| Other share class 1 to 5 | All | Description of share type | |
| Share-based payment arrangements | Share-based arrangement 1 to 8 | All | Name of share-based payment arrangement |
| Share-based payment grants | Grant 1 to 10 | All | Name or description of grant under share-based payment arrangement |
| Pension plan 1 to 6 | All | Name of defined contribution plan | |
| Post-employment benefit plans | Post-employment medical plan 1 to 2 | All | Name of defined contribution plan |
| Other post-employment benefit plan 1 to 2 | All | Name of defined benefit plan | |
| Activity | Activity 1 to 50 | Char | Description of activity |
| Material funds | Material fund 1 to 50 | Char | Description of material fund |
| Linked charity | Linked charity 1 to 5 | Char | Description of activities of linked charity |
| Institutional Grant Recipient | Name of grant recipient 1 to 50 | Char | Name of specific institutional grant recipient |
| Concessionary loans | Concessionary loan 1 to 50 | Char | Description of concessionary loan |
| Contract Type | Other contract type 1 to 2 | All | Description of other contract type |
| Contract Duration | Other duration type 1 to 2 | All | Description of other contract duration type |
| Sales Channel | Other channel type 1 to 2 | All | Description of other sales channel type |
E: Arcs and arcroles
In XBRL, an arc is an XML element that defines a directional relationship between a source concept and a target concept within a linkbase, while an arcrole is an attribute (xlink:arcrole) specifying the precise semantic nature or type of that relationship. The following arcroles are used in the taxonomies:
| # | Name | URI | Applies To |
|---|---|---|---|
| 1 | concept-label | http://www.xbrl.org/2003/arcrole/concept-label | Label arc |
| 2 | parent-child | http://www.xbrl.org/2003/arcrole/parent-child | Presentation arc |
| 3 | concept-reference | http://www.xbrl.org/2003/arcrole/concept-reference | Reference arc |
| 4 | dimension-domain | http://xbrl.org/int/dim/arcrole/dimension-domain | Definition arc |
| 5 | domain-member | http://xbrl.org/int/dim/arcrole/domain-member | Definition arc |
| 6 | dimension-default | http://xbrl.org/int/dim/arcrole/dimension-default | Definition arc |
| 7 | all | http://xbrl.org/int/dim/arcrole/all | Definition arc |
| 8 | hypercube-dimension | http://xbrl.org/int/dim/arcrole/hypercube-dimension | Definition arc |
| 9 | crossref | http://xbrl.frc.org.uk/general/types/arcroles/crossref | Definition arc |
| 10 | inflow | http://xbrl.frc.org.uk/general/types/arcroles/inflow | Definition arc |
| 11 | outflow | http://xbrl.frc.org.uk/general/types/arcroles/outflow | Definition arc |
Arcroles 1-8 are defined via XBRL International. Arcroles 9-11 are custom arcroles defined in the UK and Irish digital reporting taxonomies. Roles 4-8 are used to define dimension relationships.
F: Roles
The following are the roles used in the taxonomies:
| # | Name | URI | Applies To |
|---|---|---|---|
| 1 | Standard Label | http://www.xbrl.org/2003/role/label | Label |
| 2 | Verbose Label | http://www.xbrl.org/2003/role/verboseLabel | Label |
| 3 | Terse Label | http://www.xbrl.org/2003/role/terseLabel | Label |
| 4 | Documentation | http://www.xbrl.org/2003/role/documentation | Label |
| 5 | Reference | http://www.xbrl.org/2003/role/reference | Reference |
| 6 | FRS 101 | http://xbrl.frc.org.uk/general/ref/roles/FRS101 | Reference |
| 7 | FRS 102 | http://xbrl.frc.org.uk/general/ref/roles/FRS102 | Reference |
| 8 | Full | http://xbrl.frc.org.uk/general/ref/roles/Full | Reference |
| 9 | Full / FRS101 | http://xbrl.frc.org.uk/general/ref/roles/fullFRS101 | Reference |
| 10 | Audit Regulations | http://xbrl.frc.org.uk/general/ref/roles/AuditRegs | Reference |
| 11 | Companies Act | http://xbrl.frc.org.uk/general/ref/roles/CompaniesAct | Reference |
| 12 | Standard | http://xbrl.frc.org.uk/general/ref/roles/Standard | Reference |
| 13 | Charities SORP 2026 | http://xbrl.frc.org.uk/char/ref/roles/CharitiesSORP2026 | Reference |
| 14 | Charities SORP | http://xbrl.frc.org.uk/char/ref/roles/CharitiesSORP | Reference |
| 15 | Charities Act 2011 | http://xbrl.frc.org.uk/char/ref/roles/CharitiesAct2011 | Reference |
| 16 | FRS 103 | http://xbrl.frc.org.uk/general/ref/roles/FRS103 | Reference |
| 17 | Implementation Guidance to FRS 103 | http://xbrl.frc.org.uk/general/ref/roles/ImFRS103 | Reference |
| 18 | S3 format | http://xbrl.frc.org.uk/general/ref/roles/S3format | Reference |
| 19 | S3 additional | http://xbrl.frc.org.uk/general/ref/roles/S3additional | Reference |
The roles in rows 1-4 are standard XBRL roles, while those in rows 5-19 are for UK references. Roles in rows 13-15 relate to the Charities Taxonomy. Row 14 relates to the Charities SORP 2019; this is deprecated in Taxonomy Suites from 2026 onwards. Rows 15-19 relate to FRS 103 Insurance Contracts only.
G: References
Guides from HMRC
- XBRL guide for UK businesses
- Company Tax Return taxonomies accepted by HMRC
Guides from Companies House
- Technical interface specifications for Companies House software
Guides from FCA
- DTR 4.1 Annual financial report
- Filing of Structured Annual Financial Reports
- Company annual financial reporting in electronic format
Guides from Irish Revenue
- Irish Revenue Commissioners’ webpage with information on filing iXBRL financial statements as part of the Corporation Tax return
XBRL Specifications
- https://specifications.xbrl.org/specifications.html
RFC 2219
- Key words for Indicating Requirement levels, March 1997. Available at http://www.ietf.org/rfc/rfc2119.txt.
H: Taxonomy file structure
The namespaces of the basic schemas are based on their absolute locations. Taxonomies have below mentioned namespaces,
Namespaces of entry point schemas include the characters '-full' inserted at the end of the basic schema namespace, e.g. ...cd/yyyy-mm-dd/currencies-full/.
The following table shows the folders and files comprising the FRC Taxonomy Suite.
| Location | Prefix | Comments and namespaces |
|---|---|---|
| xbrl.frc.org.uk/ | ||
| cd/ | ||
| yyyy-mm-dd/ | ||
| business/ | ||
| bus-yyyy-mm-dd.xsd | bus | Basic schema for Business |
| bus-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/cd/yyyy-mm-dd/business | |
| bus-yyyy-mm-dd-presentation.xml | ||
| bus-yyyy-mm-dd-label.xml | ||
| bus-yyyy-mm-dd-reference.xml | ||
| bus-full-yyyy-mm-dd.xsd | bus-full | Entry point for Full Business |
| http://xbrl.frc.org.uk/cd/yyyy-mm-dd/business-full | ||
| countries-regions/ | ||
| countries-yyyy-mm-dd.xsd | countries | Basic schema for Countries and Regions |
| countries-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/cd/yyyy-mm-dd/countries | |
| countries-yyyy-mm-dd-presentation.xml | ||
| countries-yyyy-mm-dd-label.xml | ||
| countries-yyyy-mm-dd-reference.xml | ||
| countries-full-yyyy-mm-dd.xsd | countries-full | Entry point for Full Countries and Regions |
| http://xbrl.frc.org.uk/cd/yyyy-mm-dd/countries-full | ||
| currencies/ | ||
| currencies-yyyy-mm-dd.xsd | curr | Basic schema for Currencies |
| currencies-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/cd/yyyy-mm-dd/currencies | |
| currencies-yyyy-mm-dd-presentation.xml | ||
| currencies-yyyy-mm-dd-label.xml | ||
| currencies-yyyy-mm-dd-reference.xml | ||
| currencies-full-yyyy-mm-dd.xsd | currencies-full | Entry point for Full Currencies |
| http://xbrl.frc.org.uk/cd/yyyy-mm-dd/currencies-full | ||
| languages/ | ||
| languages-yyyy-mm-dd.xsd | lang | Basic schema for Languages |
| languages-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/cd/yyyy-mm-dd/languages | |
| languages-yyyy-mm-dd-presentation.xml | ||
| languages-yyyy-mm-dd-label.xml | ||
| languages-yyyy-mm-dd-reference.xml | ||
| languages-full-yyyy-mm-dd.xsd | languages-full | Entry point for Full Languages |
| http://xbrl.frc.org.uk/cd/yyyy-mm-dd/languages-full | ||
| cic/ | ||
| yyyy-mm-dd/ | ||
| cic-yyyy-mm-dd.xsd | cic | Basic schema for CIC |
| cic-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/cic/yyyy-mm-dd | |
| cic-yyyy-mm-dd-label.xml | ||
| cic-yyyy-mm-dd-reference.xml | ||
| cic34/ | ||
| cic34-yyyy-mm-dd.xsd | cic34 | Entry point for CIC34 |
| cic34-yyyy-mm-dd-presentation.xml | http://xbrl.frc.org.uk/cic/yyyy-mm-dd/cic34 | |
| dpl/ | ||
| yyyy-mm-dd/ | ||
| dpl-yyyy-mm-dd.xsd | Entry point for Detailed Profit and Loss | |
| dpl-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/dpl/yyyy-mm-dd | |
| dpl-yyyy-mm-dd-presentation.xml | ||
| dpl-yyyy-mm-dd-label.xml | ||
| dpl-core-yyyy-mm-dd.xsd | ||
| dsep/ | ||
| yyyy-mm-dd/ | ||
| AA06/ | ||
| AA06-yyyy-mm-dd.xsd | Entry point for AA06 | |
| AA06-yyyy-mm-dd-presentation.xml | http://xbrl.frc.org.uk/dsep/yyyy-mm-dd/AA06 | |
| agreement/ | ||
| agreement-yyyy-mm-dd.xsd | Entry point for DSEP Agreement | |
| agreement-yyyy-mm-dd-presentation.xml | http://xbrl.frc.org.uk/dsep/yyyy-mm-dd/agreement | |
| dsep-yyyy-mm-dd.xsd | Basic schema for DSEP | |
| dsep-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/dsep/yyyy-mm-dd | |
| dsep-yyyy-mm-dd-label.xml | ||
| dsep-yyyy-mm-dd-reference.xml | ||
| fr/ | ||
| yyyy-mm-dd/ | ||
| core/ | ||
| frc-core-yyyy-mm-dd.xsd | core | Basic schema for Core Financial Reporting |
| frc-core-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/cd/yyyy-mm-dd/core | |
| frc-core-yyyy-mm-dd-presentation.xml | ||
| frc-core-yyyy-mm-dd-label.xml | ||
| frc-core-yyyy-mm-dd-reference.xml | ||
| frc-core-full-yyyy-mm-dd.xsd | core-full | Entry point for Full Core Financial Reporting |
| http://xbrl.frc.org.uk/cd/yyyy-mm-dd/core-full | ||
| FRS-101/ | ||
| yyyy-mm-dd/ | ||
| FRS-101-yyyy-mm-dd.xsd | FRS-101 | Entry point for FRS 101 |
| FRS-101-yyyy-mm-dd-presentation.xml | http://xbrl.frc.org.uk/FRS-101/yyyy-mm-dd | |
| FRS-102/ | ||
| yyyy-mm-dd/ | ||
| FRS-102-yyyy-mm-dd.xsd | FRS-102 | Entry point for FRS 102 |
| FRS-102-yyyy-mm-dd-presentation.xml | http://xbrl.frc.org.uk/FRS-102/yyyy-mm-dd | |
| UKSEF/ | ||
| FRS-102-yyyy-mm-dd.xsd | uksef | Entry point for FRS 102-UKSEF |
| FRS-102-yyyy-mm-dd-presentation.xml | http://xbrl.frc.org.uk/uksef/yyyy-mm-dd | |
| IFRS/ | ||
| yyyy-mm-dd/ | ||
| IFRS-yyyy-mm-dd.xsd | IFRS | Entry point for UK IFRS |
| IFRS-yyyy-mm-dd-presentation.xml | http://xbrl.frc.org.uk/IFRS/yyyy-mm-dd | |
| UKSEF/ | ||
| IFRS-yyyy-mm-dd.xsd | uksef | Entry point for UK IFRS-UKSEF |
| IFRS-yyyy-mm-dd-presentation.xml | http://xbrl.frc.org.uk/uksef/yyyy-mm-dd | |
| general/ | ||
| yyyy-mm-dd/ | ||
| common/ | ||
| common-yyyy-mm-dd.xsd | common | Schema defining common tags used in all taxonomies |
| common-yyyy-mm-dd-label.xml | http://xbrl.frc.org.uk/general/yyyy-mm-dd/common | |
| ref/ | ||
| ref-yyyy-mm-dd.xsd | uk-ref | Schema defining additional reference parts used in UK |
| types/ | ||
| types-yyyy-mm-dd.xsd | types | Schema defining additional data types used in UK |
| http://xbrl.frc.org.uk/general/yyyy-mm-dd/types | ||
| reports/ | ||
| yyyy-mm-dd/ | ||
| accrep/ | ||
| accrep-yyyy-mm-dd.xsd | accrep | Basic schema for Accountant's Report |
| accrep-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/reports/yyyy-mm-dd/accrep | |
| accrep-yyyy-mm-dd-presentation.xml | ||
| accrep-yyyy-mm-dd-label.xml | ||
| accrep-yyyy-mm-dd-reference.xml | ||
| accrep-full-yyyy-mm-dd.xsd | accrep-full | Entry point for Accountant's Report |
| http://xbrl.frc.org.uk/reports/yyyy-mm-dd/accrep-full | ||
| aurep/ | ||
| aurep-yyyy-mm-dd.xsd | aurep | Basic schema for Auditor's Report |
| aurep-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/reports/yyyy-mm-dd/aurep | |
| aurep-yyyy-mm-dd-presentation.xml | ||
| aurep-yyyy-mm-dd-label.xml | ||
| aurep-yyyy-mm-dd-reference.xml | ||
| aurep-fees-yyyy-mm-dd.xsd | aurep-fees | Entry point for fees section of Auditor's Report |
| aurep-fees-yyyy-mm-dd-presentation.xml | http://xbrl.frc.org.uk/reports/yyyy-mm-dd/aurep-fees | |
| aurep-full-yyyy-mm-dd.xsd | aurep-full | Entry point for Full Auditor's Report |
| http://xbrl.frc.org.uk/reports/yyyy-mm-dd/aurep-full | ||
| direp/ | ||
| direp-yyyy-mm-dd.xsd | direp | Basic schema for Directors' Report |
| direp-yyyy-mm-dd-definition.xml | http://xbrl.frc.org.uk/reports/yyyy-mm-dd/direp | |
| direp-yyyy-mm-dd-presentation.xml | ||
| direp-yyyy-mm-dd-label.xml | ||
| direp-yyyy-mm-dd-reference.xml | ||
| direp-full-yyyy-mm-dd.xsd | direp-full | Entry point for Full Directors' Report |
| http://xbrl.frc.org.uk/reports/yyyy-mm-dd/direp-full | ||
| direp-income-yyyy-mm-dd.xsd | direp-income | Entry point for income section of Directors' Report |
| direp-income-yyyy-mm-dd-presentation.xml | http://xbrl.frc.org.uk/reports/yyyy-mm-dd/direp-income |
Financial Reporting Council
London office: 13th Floor, 1 Harbour Exchange Square, London, E14 9GE
Birmingham office: 5th Floor, 3 Arena Central, Bridge Street, Birmingham, B1 2AX
+44 (0)20 7492 2300
www.frc.org.uk
Follow us on LinkedIn